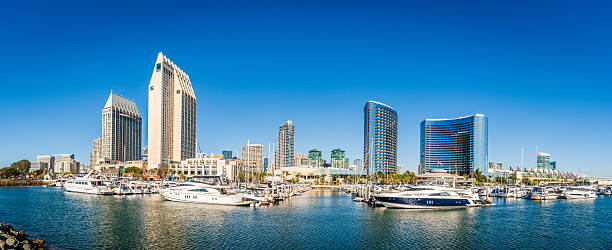
San Diego County’s housing market continues to present one of the clearest examples of a divided real estate structure in Southern California. On the surface, prices remain relatively strong and stable, supported by limited inventory and long-term coastal demand. However, beneath this pricing stability, transaction activity has slowed in a way that signals shifting buyer behavior and increasing friction in the closing process. The result is a market that appears steady in valuation but less active in execution.
Recent late summer 2026 data shows that homes are still maintaining strong price levels, yet fewer transactions are closing compared to earlier cycles. This divergence between pricing resilience and declining sales volume reflects broader affordability constraints driven by elevated mortgage rates and tightening buyer qualification standards. At the same time, San Diego’s internal market structure is becoming more segmented, with coastal, inland, and condo markets each responding differently to current conditions. Understanding these micro-market differences is essential to interpreting the true direction of the county’s housing landscape.
Coastal Submarkets: Price Stability with Limited Turnover
San Diego’s coastal regions, including areas such as La Jolla, Del Mar, and coastal Carlsbad, continue to demonstrate strong price resilience even as transaction volume softens. According to recent Realtor.com August 2026 data, median listing prices across San Diego County remain near $899,000, with coastal submarkets significantly higher depending on proximity to the ocean. While prices remain elevated, the pace of transactions has slowed, with many listings taking approximately 45 days or longer to reach contract stage.
The key dynamic in coastal areas is limited inventory turnover. Homeowners with historically low mortgage rates are reluctant to sell, contributing to a “hold effect” that keeps supply tight. This structural constraint supports pricing stability even when demand softens. However, the number of closed transactions is no longer matching prior-year activity levels, indicating that buyer participation is more selective and less urgent.
This creates a coastal market where values remain firm, but liquidity is reduced, resulting in fewer deals closing within shorter timeframes.
Inland Submarkets: Increased Flexibility but Slower Buyer Conversion
Inland areas such as Escondido, Riverside-adjacent North County corridors, and parts of East County are experiencing a different dynamic. These regions typically offer more affordability compared to coastal zones, yet even here, buyer conversion rates have slowed due to mortgage rate sensitivity.
Recent California Association of REALTORS® data indicates that while inventory has not surged dramatically, it has increased enough to extend negotiation timelines. Properties in these inland submarkets are more likely to experience price adjustments before closing, particularly if initial listing prices exceed buyer expectations. Days on market in these areas often exceed county averages, reflecting the more cautious nature of affordability-driven demand.
Unlike coastal markets, inland areas are not fully supported by wealth-driven buyers, making them more sensitive to financing conditions. As a result, even modest changes in interest rates have a noticeable impact on transaction speed and offer volume.
Condo and Attached Housing Segment: Emerging First-Time Buyer Activity
The condo and townhome segment is showing a different pattern compared to both coastal and inland detached housing markets. Recent data trends, supported by regional MLS reporting, indicate a gradual increase in buyer interest for attached housing, particularly among first-time buyers and downsizers who are priced out of single-family home ownership.
This segment is seeing relatively higher transaction activity compared to detached homes, even though pricing growth is more subdued. Condo listings are also experiencing slightly longer market times in some submarkets, but they remain more accessible entry points into the San Diego housing market. A key driver is affordability substitution, where buyers accept smaller units or shared amenities in exchange for improved price alignment.
However, even in this segment, financing constraints remain a limiting factor, meaning demand is present but not fully converting at previous cycle levels. This creates a “mid-speed market” where activity is stable but not accelerating.
Pricing Resilience vs Transaction Decline: The Core Market Split
The most important structural trend in San Diego County is the widening gap between price stability and transaction volume decline. According to Zillow and Redfin aggregated data for late summer 2026, median prices remain relatively stable year-over-year, while closed sales have declined compared to prior periods. National housing data reinforces this trend, showing U.S. existing-home sales falling to a 3.98 million annualized pace in August 2026, the lowest level in over a year, while inventory rose to 1.62 million units.
San Diego reflects this national pattern in a more concentrated form. Prices remain supported by structural scarcity in desirable submarkets, but affordability constraints are limiting the number of qualified buyers. This creates a condition where homes are valued consistently but exchanged less frequently.
The result is a market that is stable in valuation terms but weakening in liquidity terms, a distinction that is critical for understanding real market health.
San Diego County’s housing market is currently defined by a clear split between pricing strength and declining transaction velocity. Coastal areas continue to support high values due to scarcity and long-term demand, while inland and attached housing segments reflect slower absorption driven by affordability constraints. Across all submarkets, the most consistent trend is reduced buyer urgency, which is extending market times and lowering transaction frequency.
This environment does not indicate broad price deterioration but rather a shift toward lower liquidity and more selective participation. The key takeaway is that pricing strength alone no longer reflects market momentum. Instead, transaction activity and buyer conversion rates provide a more accurate measure of current conditions. San Diego remains structurally strong, but its market rhythm has clearly slowed.
Thank you for taking the time to read and reflect. I write to help people think clearly about money, business, real estate, and life — not from theory, but from decades of lived experience.
If you are navigating a financial decision, building a business, considering homeownership, or simply trying to make better use of your time and resources, I invite you to engage further.
Subscribe to The Power Is Now TV to connect with me live every weekday, Monday through Friday, from 10:00 AM to 11:00 AM PST, as we record television shows across the Power Is Now TV Network. As a subscriber, you can participate in live tapings, engage in real-time discussions, and connect directly with industry leaders.
Visit ThePowerIsNow.com to access real estate magazines, books, podcasts, television shows, and exclusive media content focused on homeownership, business, and wealth-building.
For personalized support, consulting, and advisory services in real estate, mortgages, business, and personal finance, visit EricFrazier.com to schedule a consultation and learn more about my work as your trusted advisor in business and wealth.
Eric Lawrence Frazier, MBA
Your trusted advisor in business and wealth
www.ericfrazier.com | www.thepowerisnow.com
NMLS #461807 | CA DRE #01143484
Schedule a consultation: https://calendly.com/ericfrazier/real-estate-mortgage-consultation-clients
References
California Association of REALTORS®. (2026). Southern California regional housing report. https://www.car.org
U.S. Department of Housing and Urban Development. (2026). State of housing affordability report. https://www.huduser.gov
Reuters. (2026). U.S. home sales fall amid high mortgage rates. https://www.reuters.com/business/us-existing-home-sales-drop-14-month-low-august-2026-09-10/