Mortgage interest is one of the most frequently referenced tax benefits associated with homeownership, yet it is also one of the most misunderstood. Many homeowners assume that every dollar paid toward interest automatically reduces their tax bill in a straightforward way. In reality, the deduction operates under strict rules that determine who qualifies, how much debt is eligible, and how the benefit is applied within the broader tax system. Current IRS guidance under Publication 936 establishes that taxpayers may generally deduct interest on up to $750,000 of qualifying mortgage debt for loans originated after December 15, 2017, or $375,000 for married individuals filing separately. Older loans may qualify under higher grandfathered thresholds, depending on when the debt was incurred. However, the presence of a deduction does not eliminate the cost of borrowing. Instead, it reduces taxable income, which means the benefit depends on income level, filing status, and whether a taxpayer itemizes deductions. In addition, not all home-related borrowing qualifies automatically. The use of loan proceeds plays a critical role in determining whether interest is deductible at all. Understanding these mechanics is essential for homeowners who want to evaluate borrowing decisions based on financial reality rather than assumptions about tax relief. The Real Structure of the Mortgage Interest Deduction The mortgage interest deduction applies only to “qualified residence interest,” which is generally interest paid on loans secured by a primary or secondary residence. The key condition is that the debt must be secured by the home and used for specific purposes such as buying, building, or substantially improving the property. For post-2017 loans, the IRS limits deductible interest to the first $750,000 of total qualifying mortgage debt across all eligible homes. This limit is not per property but combined across a taxpayer’s residences. This distinction is often misunderstood. A homeowner with multiple properties cannot apply the limit separately to each one. Instead, the combined balance determines how much interest qualifies for deduction. Any interest tied to debt above the threshold is not deductible, even if it is paid in full. Additionally, taxpayers must itemize deductions to benefit. If the standard deduction is higher than total itemized deductions, including mortgage interest, the taxpayer receives no incremental benefit from mortgage interest payments. Why the Deduction Does Not Reduce Interest Costs A common misconception is that the mortgage interest deduction makes borrowing cheaper in a direct sense. In practice, it does not reduce the interest charged by the lender, nor does it eliminate the obligation to pay it. It only reduces taxable income, which may or may not translate into meaningful savings depending on the taxpayer’s marginal tax rate. For example, a homeowner paying $15,000 in mortgage interest does not receive a $15,000 tax reduction. Instead, that amount is subtracted from taxable income, and the actual benefit depends on the applicable tax bracket. This creates a partial offset rather than a dollar-for-dollar reimbursement. As a result, the financial structure of a mortgage remains primarily determined by interest rates, loan terms, and amortization schedules—not tax deductions. Home Equity Debt Requires Even More Careful Analysis One of the most frequently misunderstood areas of mortgage-related tax rules involves home equity borrowing. While many assume that any loan secured by a home automatically qualifies for interest deduction, IRS rules are more restrictive. Interest on home equity loans or lines of credit is only deductible if the borrowed funds are used to buy, build, or substantially improve the home that secures the loan. If the proceeds are used for unrelated purposes—such as paying off credit cards, covering education expenses, or funding personal consumption—the interest is generally not deductible. This creates a critical distinction between “secured debt” and “qualified use.” A loan may be secured by a home but still fail to qualify for interest deduction depending on how the funds are used. This rule is especially important in periods where homeowners rely on home equity as a source of liquidity. Borrowing against a home should be evaluated based on financial necessity and repayment capacity, not assumed tax advantages. The Debt Limit Is Not a Deduction Cap Another frequent misunderstanding involves the $750,000 figure. This number is often interpreted as a limit on how much interest can be deducted. In reality, it is a limit on the amount of mortgage debt that qualifies for interest deduction. This means the IRS does not cap the interest amount directly. Instead, it limits the portion of the loan balance that generates deductible interest. If a mortgage exceeds the threshold, only a proportional share of the interest may be deductible. This distinction becomes especially important for higher-value properties or households with multiple loans. In those cases, the deductible portion of interest may be significantly lower than total interest paid. Why Borrowing Decisions Should Come Before Tax Assumptions One of the most important implications of mortgage interest rules is that borrowing decisions should not be justified by expected tax benefits. The presence of a deduction does not make debt less expensive in real economic terms. A financially sound mortgage decision should be based on interest rate affordability, income stability, long-term repayment capacity, and overall household financial resilience. Tax treatment is a secondary consideration, not a primary driver. In some cases, borrowers may take on additional debt assuming tax advantages that do not meaningfully offset long-term costs. This can lead to overleveraging and reduced financial flexibility, particularly when interest rates are elevated or income conditions change. Mortgage interest remains one of the most visible tax benefits associated with homeownership, but its actual impact is often overstated. Under current IRS rules, the deduction is limited by loan size, filing status, and use of funds, and it only applies when taxpayers itemize deductions. More importantly, the deduction does not reduce the underlying cost of borrowing. It simply adjusts taxable income, which means the real economic weight of mortgage debt remains intact. Home equity borrowing introduces additional complexity, as deductibility depends on how funds are used rather than simply how loans are structured. Ultimately, the most important
Homeownership is often marketed as a financial decision that automatically delivers tax advantages. Among the most commonly cited benefits is the ability to deduct mortgage interest, property taxes, and other housing-related expenses. While these provisions do exist within the tax code, their real-world value depends heavily on a factor that is frequently ignored in casual discussions: whether a taxpayer actually itemizes deductions or takes the standard deduction. For tax year 2026, the standard deduction is set at $32,200 for married couples filing jointly, $16,100 for single filers, and $24,150 for heads of household. This means that before any mortgage interest or property tax benefit is considered, a household must first exceed these baseline amounts through itemized deductions in order to receive any additional tax advantage. This distinction is critical because it reframes the entire conversation around homeownership and taxes. A deduction does not automatically reduce tax liability for every homeowner. Instead, it operates within a system where taxpayers must choose between two pathways—standard deduction or itemized deductions—and only one produces incremental benefit. Understanding this structure is essential for evaluating whether homeownership delivers meaningful tax savings or whether the perceived benefit is overstated in many financial decisions. The Standard Deduction Sets the Baseline for Tax Benefits The standard deduction functions as the default reduction in taxable income for most taxpayers. It is designed to simplify tax filing by allowing individuals to subtract a fixed amount without tracking or documenting specific expenses. In 2026, these amounts are substantial enough that a large portion of households benefit more from taking the standard deduction than from itemizing. For many filers, especially those without high mortgage interest or significant deductible expenses, the standard deduction effectively replaces itemized deductions entirely. This is the first major misconception in homeownership tax planning: many households assume they are receiving additional tax benefits from owning a home when, in reality, they are simply using the standard deduction that would apply regardless of homeownership status. The implication is straightforward. If a homeowner’s total itemizable expenses—including mortgage interest, property taxes, and charitable contributions—do not exceed the standard deduction threshold, then the mortgage interest deduction provides no additional financial benefit. Why Mortgage Interest Often Fails to Create Additional Tax Savings Mortgage interest is frequently presented as a key advantage of homeownership, but its actual impact depends on both loan structure and tax filing strategy. The IRS allows interest deductions on qualifying mortgage debt, but only if the taxpayer itemizes deductions instead of using the standard deduction. This creates a two-layer requirement: The taxpayer must have eligible mortgage interest. Total itemized deductions must exceed the standard deduction. If either condition is not met, the mortgage interest deduction does not produce incremental tax savings. This is particularly important in the current housing environment, where higher standard deduction levels mean fewer households benefit from itemizing at all. As a result, many homeowners who assume they are receiving a tax benefit from mortgage interest are actually receiving no additional advantage beyond what non-homeowners already receive through the standard deduction. The Role of Property Taxes in the Itemization Equation Property taxes are another component often included in discussions about homeownership tax benefits. However, like mortgage interest, property taxes only contribute to savings if the taxpayer itemizes deductions. Even when combined with mortgage interest, charitable contributions, and other eligible expenses, many households still do not surpass the standard deduction threshold. This is especially true for first-time buyers with smaller mortgages or those who have refinanced into lower-interest loans. In practice, this means that property taxes often represent a cash expense without producing a corresponding federal tax offset for a large share of homeowners. The tax code does not reimburse these payments directly; it only allows them to be deducted under specific conditions that many taxpayers do not meet. Why the Tax Benefit Is Often Misunderstood The misunderstanding around homeownership tax benefits typically comes from conflating three separate ideas: Paying mortgage interest Having deductible expenses Actually reducing taxable income beyond the standard deduction These are not interchangeable. A homeowner can pay significant interest and still receive no additional tax benefit if itemization is not advantageous. Additionally, tax brackets further complicate perception. A deduction reduces taxable income, not tax owed directly. The actual savings depend on the taxpayer’s marginal tax rate, meaning the benefit varies widely between households. This structure often leads to overstated expectations of tax savings when purchasing a home, especially when financial decisions are based on simplified assumptions rather than full tax calculations. Why Homeownership Still Makes Sense Without Tax Assumptions Even without assuming major tax benefits, homeownership can still be financially justified. The economic case for owning a home is typically built on factors such as long-term housing stability, forced equity accumulation through mortgage repayment, and potential appreciation over time. These drivers operate independently of tax deductions. In many cases, the decision to purchase a home is strengthened or weakened more by interest rates, purchase price, insurance costs, and maintenance obligations than by tax considerations. This distinction is important because it shifts homeownership analysis away from assumed tax advantages and toward measurable financial fundamentals. The idea that homeownership automatically delivers significant tax savings is often overstated. For tax year 2026, the standard deduction of $32,200 for married couples, $16,100 for single filers, and $24,150 for heads of household sets a high threshold that many taxpayers do not exceed through itemized deductions alone. As a result, mortgage interest and property tax deductions only provide additional value when a household’s total eligible expenses surpass that baseline. For many homeowners, this does not occur, meaning the expected tax benefit is either reduced or entirely absent. The key takeaway is that homeownership decisions should not rely on assumed tax advantages. The financial strength of buying a home should be evaluated through affordability, long-term stability, and overall wealth-building potential rather than expectations of automatic tax relief. Understanding how the standard deduction interacts with itemized deductions provides a more accurate foundation for making informed housing decisions. Thank you for taking the time
You need to be logged in to view this content. Please Log In. Not a Member? Join Us
The housing market is no longer moving in a single direction nationwide. Instead, conditions are splitting across regions, price ranges, and inventory levels, creating very different experiences depending on where buyers and sellers are active. In some metropolitan areas, homes are still moving quickly with limited negotiation room. In others, listings are staying on the market longer, price reductions are increasing, and buyers are beginning to regain leverage in ways not seen in several years. One of the clearest indicators of this shift is the broad expansion of buyer-friendly conditions across major metros. Recent market tracking shows that 70% of the 100 largest metropolitan areas are now either leaning toward buyers or actively moving in that direction. That is a significant increase from 52% a year earlier and only 37% in 2019. Even more striking, nearly 19% of those markets are now classified as outright buyer’s markets, with a strong concentration in Southern regions where 18 of those 19 metros are located. These changes reflect more than short-term fluctuation. They point to a structural transition driven by inventory growth, affordability constraints, and slower absorption rates. Understanding how these forces interact provides a clearer view of where negotiation power is shifting and what that means for both sides of a transaction. Expanding Inventory and Slower Market Absorption Inventory has become one of the most important drivers of current housing conditions. After years of tight supply, many metropolitan areas are now experiencing a steady increase in active listings. This shift is changing how quickly homes sell and how aggressively buyers must compete. In several regions, homes are now spending 10 to 20 additional days on the market compared to previous high-demand cycles. Instead of receiving multiple offers within days, properties often remain active long enough for sellers to reassess pricing strategy. This extended exposure naturally increases the likelihood of price reductions, particularly when initial listing prices are set above current market expectations. At the same time, absorption rates have slowed. Fewer homes are being purchased within short timeframes, which allows inventory to accumulate. In practical terms, this means buyers have more comparable options available at any given time, reducing urgency and increasing negotiating power. Housing construction trends also contribute to this environment. While building activity remains present, it is uneven across regions due to financing costs, labor constraints, and developer caution. In some metros, reduced new construction has helped stabilize prices, but in others, resale inventory growth has outpaced demand, contributing to softer conditions. Affordability Pressures Reshaping Demand Mortgage conditions continue to play a central role in shaping buyer behavior. Compared to previous years of historically low borrowing costs, current mortgage rates remain significantly higher, which directly reduces purchasing power across most income levels. Even small fluctuations in interest rates can materially affect affordability. For many buyers, the difference translates into tens of thousands of dollars in reduced borrowing capacity, particularly in mid-range price segments. This has created a more cautious buyer pool, where decisions take longer and comparisons are more detailed. As demand has softened, negotiation activity has increased. Seller concessions such as closing cost assistance, inspection repairs, and price adjustments are becoming more common in several markets. These concessions signal a shift away from competitive bidding environments toward more balanced transaction structures. Price sensitivity has also increased. Homes that remain on the market beyond the typical listing window are more likely to undergo price adjustments. This is especially evident in metros where inventory growth has outpaced buyer demand recovery. Regional Market Divergence and Localized Conditions One of the most defining characteristics of the current housing environment is the lack of uniformity across regions. Instead of a national trend, there are multiple localized markets operating under different conditions at the same time. Nearly 18 of the 19 identified buyer’s markets are concentrated in the Southern region, where inventory expansion has been more pronounced. These areas are experiencing stronger buyer leverage due to higher supply levels relative to demand. Other regions continue to show tighter conditions, particularly where construction is limited or population growth remains strong. However, even in these areas, early signs of moderation are beginning to appear, including longer listing durations and more frequent price adjustments. Key indicators separating market conditions now include: Year-over-year inventory growth exceeding 10% in several metros Days on market extending beyond 45–60 days in softer regions Increasing frequency of price reductions within the first 30 days of listing Sale-to-list price ratios moving closer to equilibrium rather than above asking These indicators highlight that market power is no longer concentrated on one side of the transaction. Instead, it is shifting based on local supply-demand balance. The housing market is moving into a more balanced phase, with clear evidence of buyer-friendly conditions expanding across a growing number of metropolitan areas. With 70% of major markets now leaning toward buyers or shifting in that direction, the environment is increasingly defined by longer listing times, rising inventory, and reduced urgency among buyers. At the same time, conditions remain highly localized. Some regions continue to experience strong demand, while others are seeing meaningful softening. This divergence reinforces the importance of evaluating real estate at the local level rather than relying on national averages. The most important takeaway is that leverage in today’s housing market is fluid. It changes based on timing, pricing strategy, and regional supply conditions. Buyers and sellers who understand these shifts are better positioned to navigate decisions with clarity and confidence. Thank you for taking the time to read and reflect. I write to help people think clearly about money, business, real estate, and life — not from theory, but from decades of lived experience. If you are navigating a financial decision, building a business, considering homeownership, or simply trying to make better use of your time and resources, I invite you to engage further. Subscribe to The Power Is Now TV to connect with me live every weekday, Monday through Friday, from 10:00 AM to 11:00 AM PST, as we record television shows across the
Residential housing activity has entered a phase where transaction volume no longer moves in step with price direction. In many periods, rising prices and rising sales activity tend to align, or falling prices are paired with increased buyer participation. That pattern is no longer consistent. Instead, the current environment reflects a disconnect between pricing stability and slowed sales velocity, creating the impression that the market is stalled even while values remain relatively firm in several regions. Recent national housing data highlights this tension. Existing-home sales declined 1.7% in July, reaching a seasonally adjusted annual pace of 4.06 million units. Despite the monthly decline, sales activity still remained 0.7% higher than the same period a year earlier. At the same time, the national median existing-home price rose to $434,100, reflecting a 2% year-over-year increase. Inventory levels also expanded slightly, reaching approximately 4.6 months of supply, which is generally considered closer to balanced conditions compared to the extremely tight supply seen in previous cycles. These figures reveal an important reality: weak sales volume does not automatically translate into falling prices. Instead, the market is being shaped by a combination of elevated mortgage rates, constrained affordability, and homeowner reluctance to give up historically low financing. Understanding how these forces interact provides clarity on why homes are taking longer to sell and why expectations of a rapid price correction have not materialized in many areas. Mortgage Rates and the Affordability Barrier The most influential factor controlling current housing activity is the cost of borrowing. Mortgage rates remain significantly higher than the levels that fueled previous waves of strong demand. Even small rate changes can have a meaningful impact on monthly payments, particularly for mid-priced homes where affordability margins are already tight. This rate environment has reduced the number of qualified or willing buyers in the market. Instead of broad participation, demand is now more selective, with many potential buyers choosing to delay decisions or adjust price expectations downward. The result is slower absorption of available listings, even in markets where inventory has increased. At the same time, homeowners who locked in lower mortgage rates in previous years are less inclined to sell. Moving would often require taking on a substantially higher borrowing cost, even if the next home is similarly priced. This “rate lock effect” has reduced the number of resale listings entering the market, preventing supply from expanding at a pace that would typically drive sharper price declines. Why Sales Are Slowing Without a Price Collapse A common assumption in cooling markets is that lower sales activity automatically leads to falling home prices. Current conditions challenge that assumption. Even as transaction volume has softened, prices have remained relatively stable, with the national median reaching $434,100 and posting a 2% annual increase. One reason for this stability is constrained supply in key segments. While inventory has improved to roughly 4.6 months nationally, it is still uneven across regions and price tiers. Entry-level and mid-range homes remain relatively limited in many areas, which supports pricing even when demand weakens. Another factor is seller behavior. Many homeowners are not under pressure to sell quickly. Without distress-driven inventory entering the market, pricing tends to adjust more slowly. This creates a situation where homes may take longer to sell, but values do not experience sharp declines unless broader economic conditions shift significantly. The interaction between slower demand and controlled supply results in a market that feels stalled rather than collapsing. Homes remain listed longer, negotiations become more common, and pricing adjustments occur gradually instead of abruptly. Inventory Levels and Market Balance Signals The current inventory level of approximately 4.6 months of supply is an important benchmark. Traditionally, a 4–6 month range is considered a balanced market, where neither buyers nor sellers hold dominant control. However, balance in volume does not always translate into balance in pricing behavior. In some metropolitan areas, inventory is still tight enough to support stable pricing. In others, increased supply combined with weaker demand has created more negotiable conditions. This variation reinforces the importance of local analysis rather than relying solely on national averages. In markets where listings are growing faster than sales, buyers are beginning to see more negotiation flexibility. In contrast, areas with limited new listings continue to support stronger pricing even with slower turnover. This divergence is one of the defining features of the current housing cycle. Why a “Crash Expectation” May Not Align With Current Conditions The idea that slowing sales automatically lead to a significant price collapse does not fully align with current market dynamics. Unlike previous downturns driven by oversupply or distressed selling, today’s environment is shaped more by affordability constraints and financing conditions than by forced liquidation. Homeowners with low fixed mortgage rates are largely staying in place, reducing the volume of motivated sellers. At the same time, lending standards remain more structured compared to earlier high-risk lending periods. These factors limit the type of widespread forced inventory that typically drives sharp price declines. Instead, the market is adjusting through time rather than price acceleration or collapse. Homes stay listed longer, negotiations increase, and price changes occur gradually depending on local demand conditions. This creates a slower-moving correction pattern rather than a rapid downturn. The housing market is currently defined by a clear disconnect between transaction volume and price movement. Existing-home sales have softened to a 4.06 million annualized pace, yet median prices continue to hold above $434,000 with modest annual growth. Inventory has improved to a more balanced level, but mortgage rates and homeowner reluctance to sell remain powerful stabilizing forces. Rather than signaling a collapse, the current environment reflects a market adjusting to higher financing costs and uneven supply conditions. Sales are slowing not because demand has disappeared, but because affordability constraints and rate sensitivity are reshaping buyer participation. At the same time, limited distress and cautious seller behavior are preventing sharp downward pressure on prices. The most important takeaway is that market movement is no longer driven by a single national force. It
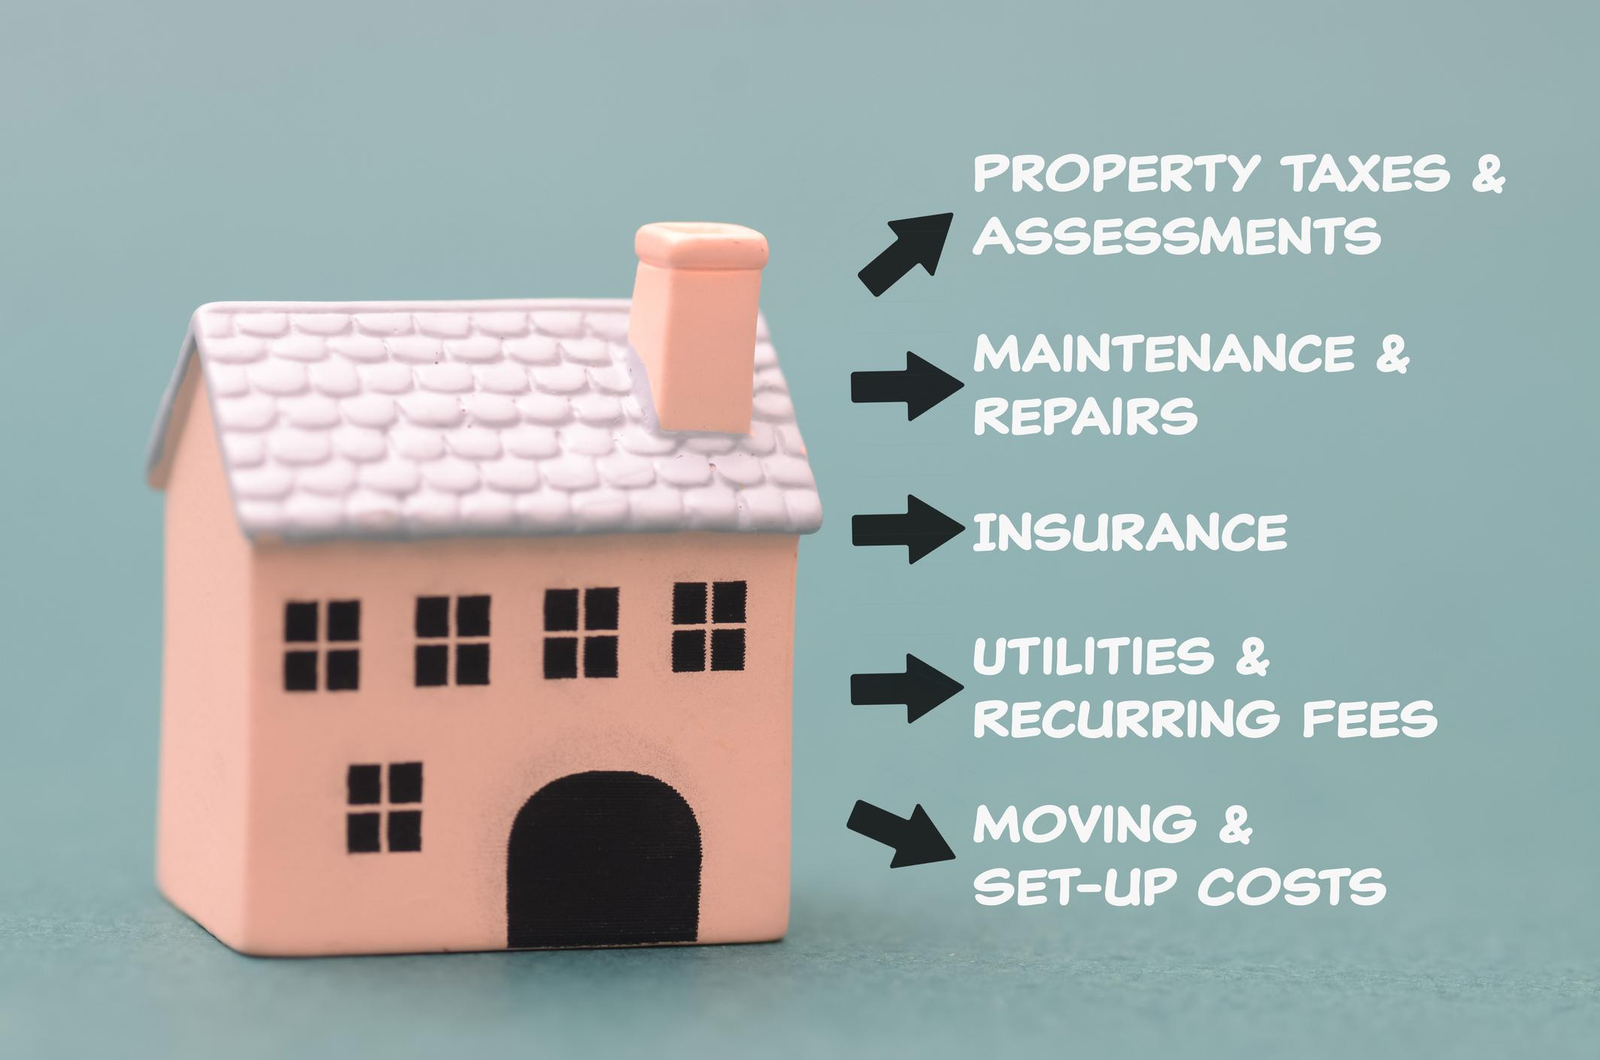
Mortgage performance data is often interpreted through a single headline number, but that surface-level reading can hide important shifts underneath. While overall delinquency rates may appear stable or even improving in the short term, the deeper breakdown of loan performance can tell a more complex story about household financial pressure and emerging vulnerability in parts of the borrower population. Recent results from the Mortgage Bankers Association’s National Delinquency Survey for the second quarter of 2026 show that the overall mortgage delinquency rate declined slightly to 4.37%, down seven basis points from the previous quarter. At first glance, this suggests a stable housing finance environment. However, the same report also shows that the delinquency rate remains 44 basis points higher than a year earlier, indicating that year-over-year stress is still building in the system. More importantly, seriously delinquent loans have increased for four consecutive quarters, pointing to growing strain beneath the surface. This combination of stable headline performance and rising severe delinquency highlights an important distinction in housing finance: not all borrowers experience market conditions in the same way. Understanding what is driving this divergence requires looking beyond the headline rate and focusing on financial resilience, household buffers, and exposure to economic shocks. The Meaning Behind Stable Delinquency Rates A delinquency rate of 4.37% suggests that the majority of homeowners are still keeping up with their mortgage obligations. In isolation, this number could be interpreted as a sign of stability in the housing finance system. However, mortgage performance data is layered, and the distribution of stress matters as much as the overall rate. The fact that delinquency is slightly lower than the previous quarter indicates short-term improvement in payment performance. However, the year-over-year increase of 44 basis points signals that underlying pressure has not fully eased. More importantly, the increase in seriously delinquent loans for four consecutive quarters suggests that while many borrowers are managing payments, a smaller segment is falling further behind. This divergence is often the first stage of financial stress becoming more concentrated. Rather than widespread default risk, the pattern points to growing vulnerability within specific household segments. Why Some Households Are Becoming More Vulnerable The current mortgage environment is shaped by multiple overlapping pressures that extend beyond the mortgage payment itself. While borrowers may qualify for a loan under underwriting standards, ongoing affordability depends on broader financial stability. Several factors are contributing to increased vulnerability: Emergency savings depletion after periods of higher inflation and elevated living costs Rising insurance premiums, particularly in regions exposed to climate-related risks Higher property tax assessments tied to earlier home value appreciation Maintenance and repair costs that increase with aging housing stock Income variability, especially among households with gig-based or variable earnings Employment uncertainty, which directly affects repayment capacity Even if mortgage payments remain consistent, these additional pressures can reduce household flexibility. When combined, they make it more difficult for borrowers to absorb unexpected financial shocks. The Importance of Seriously Delinquent Loans One of the most important warning signals in the latest data is the continued rise in seriously delinquent loans. These are typically borrowers who are significantly behind on payments, often 90 days or more. While the overall delinquency rate provides a broad snapshot, the serious delinquency category reveals where financial stress is becoming structural rather than temporary. A four-quarter increase in this segment suggests that some households are not just experiencing short-term cash flow issues but are facing sustained difficulty in maintaining mortgage payments. Historically, increases in serious delinquency often appear before broader stress becomes visible in foreclosure trends or forced sales activity. However, this does not necessarily imply an immediate housing downturn. Instead, it reflects uneven financial resilience across different borrower groups. Why Strong Home Prices Do Not Eliminate Risk A common misconception is that stable or rising home prices automatically protect households from financial stress. While equity can provide a buffer, it does not eliminate monthly payment pressure or liquidity constraints. Even homeowners with positive equity can experience difficulty meeting obligations if income stability weakens or expenses rise faster than expected. In such cases, equity alone does not resolve short-term cash flow challenges. This is why delinquency trends can rise even in environments where housing values remain relatively firm. Price stability and borrower stability are related but not identical. Financial Resilience Matters More Than Qualification The current environment highlights an important distinction between qualifying for a mortgage and sustaining homeownership over time. Underwriting standards focus on whether a borrower can afford a loan at the point of origination. However, long-term success depends on whether the household maintains sufficient liquidity after closing. Key indicators of stronger financial resilience include: Adequate emergency savings covering several months of expenses Stable employment or diversified income sources Conservative debt levels beyond the mortgage Ability to absorb increases in insurance or maintenance costs Financial flexibility to handle temporary income disruptions Without these buffers, households become more sensitive to economic shifts, even if they were initially approved for financing under standard guidelines. The latest mortgage delinquency data presents a nuanced picture. While the overall delinquency rate has edged down to 4.37%, underlying indicators show increasing stress in the form of rising year-over-year delinquency and a fourth consecutive quarterly increase in seriously delinquent loans. This divergence suggests that financial pressure is not widespread but is becoming more concentrated among vulnerable households. Rather than signaling a systemic breakdown in mortgage performance, the data points to a growing gap in financial resilience. Many homeowners continue to manage payments successfully, while others face increasing difficulty absorbing economic shocks such as rising costs, income variability, and unexpected expenses. The key takeaway is that mortgage stability depends on more than the ability to qualify for a loan. It depends on long-term financial capacity to withstand change. In that sense, the most important risk factor in today’s housing market is not price movement or interest rates alone, but household liquidity and financial preparedness beyond the mortgage payment itself. Thank you for taking the time to read and reflect. I write to
I have worked with homebuyers for years—across boom markets, rate shocks, bidding wars, and “normal” markets that never feel normal when you are the family trying to buy your first home. I have sat at kitchen tables, reviewed paystubs and bank statements, explained Loan Estimates line by line, and watched the same emotional pattern repeat itself with different faces. Most buyers want more house than they can afford. I understand why. A family is living in a 1,000-square-foot apartment with two or three children. Somebody is always in somebody’s way. Privacy is gone. Noise is constant. Stress is a background hum that never turns off. They do not only want space—they want relief. They want dignity. They want a fresh start. So the dream starts assembling itself in their minds before they ever talk to a lender. The wife imagines a big kitchen—granite countertops, an island, new appliances, that magazine-spread feeling of “I made it.” The husband imagines a three-car garage, a workshop corner, a big backyard, a place where the kids can run. Both of them imagine the neighborhood: tree-lined streets, safety, good schools, a white picket fence, the feeling of finally being “out” of the apartment life. Nothing about wanting better is wrong. The danger begins when the picture in their mind costs two or three times more than their actual budget—and yet they still qualify for the loan. That single moment—the phone call or email that says “Congratulations, you’re pre-approved”—becomes psychological permission. It feels like the bank just certified their dream. It feels like a professional, objective third party just validated what their heart already wanted. It feels like the argument is over. But what most buyers do not understand is this: a pre-approval is not a budget. And that is where the dream becomes the trap. Because in reality, many buyers buy a house that fits their pre-approval but not their budget. They will make it work. They will stretch. They will hustle. They will take on overtime. They will cut corners. They will sacrifice. They will tell themselves, “It’s only for a season,” and then that season becomes a decade. They will feel proud because they moved into a better neighborhood. They will feel accomplished because their friends are impressed. They will feel successful because they “leveled up.” And then, for many, the pride slowly turns into pressure—quiet at first, then constant. The dream flips. The dream becomes a nightmare, not because homeownership is bad, not because lending is immoral, and not because the buyer is foolish. The nightmare happens because the foundation was wrong. They did not need the biggest house they could qualify for. They needed a house that fits their budget. They needed a house they can actually afford, that they can actually pay off, that gives them shelter, stability, and the margin to build real wealth. That sentence sounds simple. It is not simple in practice, because it requires a person to stop using the house as a statement of identity and start treating the house as a disciplined financial decision. To do that, we have to get clear about two things that Americans routinely confuse: What a budget is What a mortgage really is 1) Budget vs. Pre-Approval: Two Different Universes Now, in case you are lost, let me define what a budget is—because a budget is not a mortgage pre-approval. A pre-approval is what a lender is willing to lend you based primarily on your credit profile, assets, and gross income, using underwriting guidelines and ratios that are designed to protect the lender. A budget is what your life can sustain based on take-home pay, real living expenses, future goals, and the reality that problems do not ask permission before they show up. That difference is not a minor technicality. That difference is the line between a mortgage that serves your life and a mortgage that consumes your life. The first difference: a pre-approval does not take into consideration your living expenses A lender’s underwriting model is not built around your actual household rhythm. Lenders are not fully counting, in the way you experience them: groceries and household supplies gasoline, tolls, commuting, and parking utilities that rise with square footage childcare and school costs cell phones and the internet car insurance, repairs, and replacements health insurance considers payroll deductions, not your lived medical reality prescriptions, copays, dental work, and “surprise” medical bills family obligations (supporting parents, helping siblings, church giving, community commitments) the cost of being alive in a modern economy Some of these items are “considered” indirectly through residual income calculations in certain programs, or through general assumptions, but that is not the same as your real monthly cash flow. Most buyers discover this only after they move in—when the new house has new costs, the utility bill rises, and the “unknown unknowns” show up. The second difference: a pre-approval is based on gross income, not take-home pay This is where the illusion becomes dangerous. Many underwriting ratios are based on gross income—income before taxes, before insurance, before retirement contributions, before payroll deductions. But you do not live on gross income. You live on take-home pay. So when a buyer says, “The bank says my debt-to-income ratio is 45%,” they often do not realize what that means in real life. Once you remove taxes and deductions, the household’s actual debt burden can feel like 70% to 75% of take-home pay, especially when the mortgage is at the top of the pre-approval range. That leaves a thin slice of cash flow for everything else. Food. Gas. Utilities. Insurance. Maintenance. Emergencies. Saving. Investing. Living. And here is the part nobody wants to admit until the stress becomes permanent: You cannot build wealth without margin. If your housing decision kills your margin, you might still be “approved,” but you are not stable. You are surviving. That is what happens when people treat pre-approval as permission instead of treating a budget as protection. 2) Margin: The Difference Between Homeownership and
Sellers, It’s Time to Pay It Forward Hello fellow homeowners, Are you contemplating selling your home but find yourself facing uncertainties? Perhaps the current climate of high interest rates and escalating real estate prices has you hesitating. It’s crucial to recognize that the time has come to move forward while also remembering where you started. Let’s take a moment to reminisce. Do you recall the effort and dedication you invested when you purchased your first home? Did you rely on VA, USDA, or FHA loans, or did you benefit from a city grant or parental support? Did you experience housing shortages like those we face today, and what was your interest rate – 7% or even lower? If these situations sound familiar, it’s time to contemplate giving back. Now, here’s the catch: if you haven’t considered selling your home with this perspective, it may be because you’ve been working with a listing agent focused on a quick sale, possibly neglecting diverse groups of potential buyers. Here’s the difference we advocate for. Let’s embrace the idea of opening our doors to all types of buyers, including those who may not have a 20% down payment or those relying on VA or FHA loans. It’s time to discard preconceptions that a perfect buyer fits a specific mold. Let’s celebrate diversity and inclusion. So, who is this seller we’re addressing? It could be someone from a family that never owned a home, a single parent striving to make ends meet, or an individual who overcame adversity to succeed. These are the sellers we focus on today – those who faced challenges and received assistance along the way. We’d like to share inspiring stories of individuals who transformed their lives thanks to the support they received. Imagine someone who grew up in poverty, earned a scholarship, went to college, and purchased their first home with the help of education, grants, and scholarships. These stories illustrate the profound impact of a little assistance. Now, what’s your story, Mr. or Mrs. Seller? Who extended a helping hand when you needed it most? Are you following your realtor’s advice or listening to your heart? It’s time to reflect on your journey and to pay it forward. By doing so, you can contribute to addressing the ongoing housing challenges in our nation. But there are important considerations to address. Some agents discourage buyers from writing motivation letters or sharing personal details due to concerns about fair housing laws. However, sharing this information can help ensure no discrimination occurs. It’s time to be more transparent about clients’ circumstances and stories. Let’s document all offers received and have objective reasons for selecting an offer, beyond just the highest price. Here’s our call to action for sellers: Recognize your home’s value and consider offering a seller credit, typically around 3%, to cover first-time homebuyers’ closing costs. Prioritize the highest offer, without letting the buyer’s financing type influence your decision. Avoid judgment of buyers using 100% financing or down payment assistance, and let’s not discriminate against the working class. Base decisions solely on merit and avoid discrimination based on race, color, place of origin, or sexual orientation. While you may not be privy to a buyer’s characteristics, your agent might be. Request motivation letters to understand your buyer’s story better. Your home may hold greater significance to them than you realize. Sellers, you have the power to make a meaningful difference in the lives of First Time Homebuyers. If your home has been on the market for awhile, consider offering a seller credit to cover closing costs and or for repairs, before lowering the price. Your challenge in selling your property quickly may be more about the terms or conditions of the property and not the price. Speak to your agent, share your story, and express your willingness to assist someone in need.Reach out to your community and express your desire to sell your home to someone who truly needs it – perhaps a member of your church, tribe/club, nonprofit, or extended family. If you’re contemplating selling, reach out to me, and I can connect you with agents who understand the importance of paying it forward. Remember, tomorrow never arrives. The time for change is now, and it starts with you, the seller. Sellers, let’s make the world a better place, one home at a time. If you are interested in discussing your plans for real estate and or business and need assistance, please contact me at 714-475-8629. I am an advisor with expertise in various fields, including real estate, lending, business, media, ministry, non-profit, and personal finance. Real Estate Brokers License CA DRE 01143484, Mortgage Lending: CA NMLS 461807. New boost
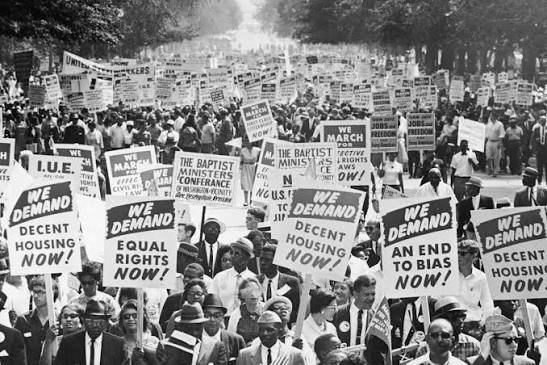
Hello, fellow homeowners! If you’re following along, you’ve already taken the first step in understanding the importance of paying it forward when selling your home. But now, it’s time to dive deeper and explore how you can unleash the full potential of your home. You see, your home is not just a structure with four walls and a roof. It’s a place where dreams are born, memories are made, and lives are transformed. So, let’s talk about how you can make a difference and leave a lasting impact. 1. Understanding the Power of EquityYou’ve probably seen the value of your home increase over the years. The equity you’ve built is not just a number on paper; it’s a tool that can change someone’s life. By recognizing the potential in your equity, you can help first-time homebuyers get their foot in the door. Imagine offering a small portion of your home’s equity to cover a buyer’s closing costs. It may be just 3%, but that 3% can make all the difference for someone trying to afford their first home in a market where prices seem out of reach. It’s not about taking less; it’s about helping others achieve their dreams. 2. Looking Beyond Financing Types When it comes to accepting offers, let’s throw out the outdated notions of the “perfect” buyer. It’s not about whether they can put 20% down or have a conventional loan. It’s about embracing diversity and inclusion in the real estate market. Don’t discriminate against those using VA, FHA, or down payment assistance. These programs are lifelines for many aspiring homeowners. Just as someone once helped you or your family, you can pay it forward by welcoming all types of financing. 3. No to Discrimination Discrimination in the contemporary real estate landscape can manifest in various forms, posing significant challenges to housing equity and inclusivity. One common issue is racial and ethnic discrimination, where individuals face unequal treatment or are steered away from certain neighborhoods based on their background. Discrimination against protected classes, including gender, age, disability, and familial status, remains a persistent concern, leading to housing denials and unequal terms. Discrimination against the LGBTQ+ community is also prevalent, with individuals encountering bias, hostility, or housing denial based on their sexual orientation or gender identity. Moreover, income and financing discrimination can occur when sellers or landlords favor those with higher incomes or specific financing types, often overlooking potential buyers with government-backed loans or alternative income sources. Implicit bias can inadvertently sway real estate professionals’ actions, even when no conscious discriminatory beliefs are held. It’s crucial to ensure that discrimination has no place in your real estate transaction. Your agent should not be judging buyers based on their race, color, place of origin, or sexual orientation. We often don’t know the buyer’s story, but it’s vital to make your expectations clear to your agent. By accepting offers without bias, you can make a significant impact in leveling the playing field for all prospective homeowners, irrespective of their background. 4. The Power of the Buyer’s Story Let’s talk about motivation letters. While some shy away from them, we encourage you to embrace them. In California, it’s not illegal to request these letters, and they can provide you with a glimpse into the lives of those eager to buy your home. Wouldn’t you like to know if the person buying your house served in the military and sacrificed for their country? How about the newlyweds with children who have special needs? Each buyer has a unique story, just as you do. These stories are woven into the tapestry of our lives, and they deserve to be heard. 5. Making Extraordinary Times Count We live in extraordinary times, and sometimes it takes extraordinary measures to help people find their way into a home. Sellers like you have the power to make a significant difference in someone’s life. Your willingness to understand and support buyers can be a beacon of hope in a challenging real estate market. So, if you are selling your home and you want to make to an impact on a stranger and make the world a better place and just a little easier on the life on next family homeownership dreams, here’s what I encourage you to do: Equity is a gift that is rarely earned in real estate: We are all benefiticiary of an extraordinary ecomony due to the 2008 Great Financial Crisis. The low inventory and high demand has resulted in abnormally high home prices. We all have more equity in our homes that we could have ever imagine. Recognize the power of your home’s equity and consider offering a seller credit to cover closing costs. It’s a small step that can change someone’s life. Their is great power and reciporical benefits in giving and helping others. Accept the Highest Offer: Just becuase prices are high and you have more equity than you could have ever imagin, it doesn’t mean you should not accept the highest offer. Recieve the windfall from the wise decision to buy years ago. But don’t consider the type of financing the buyer is using when making your decision. Your purchase contract has contingencies that are design to protect the seller and buyer and to ensure that the transaction will close in timely manner and with adequate financing. Do not discriminate based on the type of financing the buyer is using. Say No to Discrimination: The civil rights movement (1865-1896) aimed to eliminate racial discrimination against African Americans and improve their educational and employment housing opportunities. While the Civil Rights Act of 1866 prohibited discrimination in housing, there were no federal enforcement provisions. The 1968 Fair Housing Act expanded on previous acts like 1964 Civil Rights Act and the 1963 Rumford Fair Housing Act in California, and prohibited discrimination concerning the sale, rental, and financing of housing based on race, religion, national origin, and since 1974, sex. Since 1988, the act protects people with disabilities and families with children. Pregnant women
Hello, you awesome home owners and aspiring home sellers! You’ve been part of our journey, so you know how much you can impact the lives of others by helping them find their ideal homes. But now, let’s talk about something magical – the ripple effects of home sales. Did you know that every time you sell your home, you’re not only making a profit for yourself, but also creating opportunities for other people? Think about it: when you sell your home, you free up space for a new buyer who might be looking for a bigger or better place to live. And when you buy a new home, you’re supporting the seller who might be downsizing or relocating. And so on and so forth. So you see, selling your home is not just a personal decision, but a powerful one that can make a positive difference in the world. That’s why we’re here to help you make the most of it. The Butterfly Effect of Real Estate Do you know the butterfly effect? It’s the idea that small actions can lead to big changes. Well, in the world of real estate, selling your home can start a domino effect that benefits not just one, but many lives.Think about it, by agreeing to a fair offer from a buyer, you’re not just handing over the keys to a new owner; you’re creating a home where a family will make their memories. You’re adding value to a neighborhood, and your generosity might encourage others to do the same. But that’s not all. Selling your home also helps the economy, the environment, and the community. How? Well, when you sell your home, you create jobs for real estate agents, contractors, movers, inspectors, and other professionals. When you upgrade your home, you install energy-efficient and eco-friendly features that reduce your carbon footprint and save resources. And when you move to a new home, you join a new community and make new friends.So you see, selling your home is not just a personal choice, but a powerful one that can make a positive difference in the world. That’s why we’re here to help you make the best of it. Whether you’re ready to sell your home now or just curious about the process, we’re happy to answer any questions you might have and guide you through every step of the way. Home Sweet Home Consider what home means to you. It’s not just a place with walls and a roof; it’s where life happens. It’s where kids learn and grow, where families share joy and sorrow, and where you find peace and rest. By selling your home with a generous spirit, you’re giving someone the opportunity to experience that same happiness and love.But you’re also doing more than that. You’re creating a legacy, a story that will live on in your home and in the hearts of those who will live there. You’re leaving behind memories, lessons, and values that will inspire and guide the new owners. You’re passing on a gift, a treasure that will enrich and bless their lives. The Joy of Homeownership Owning a home isn’t just about bricks and mortar; it’s about weaving your story into the very fabric of its walls. It’s that warm feeling when you walk through the front door, knowing that you’re not just stepping into a house, but into a sanctuary where life unfolds, where you build a lifetime of cherished moments. It’s that sense of stability, the reassurance that you have a place to call your own, a space where your roots can run deep, and your dreams can take flight. As a seller, you have the power to be the bearer of this joy. When you swing open your doors and welcome buyers from diverse backgrounds, you’re not just selling a house – you’re offering a chance at a beautiful journey. You’re passing on the keys to a world of possibilities, to a place where someone can start crafting their own story, make their own mark, and experience the same sense of belonging and pride that you’ve felt. It’s more than a transaction; it’s a heartwarming exchange of dreams and aspirations. Your home is a canvas, and each new owner adds their own strokes to the masterpiece of its history. So, be open, be inclusive, and be a part of creating these magical moments for others. Building a Stronger Community Picture this: neighborhoods that come alive with a vibrant blend of stories and backgrounds, where unity dances hand in hand with diversity. When you, as a seller, embrace inclusivity and say no to discrimination, you’re not just facilitating a home transaction; you’re weaving the threads of a diverse tapestry that makes your community stronger. It’s about creating a space where the young couple from the nearby town and the family who recently arrived from across the country can find common ground. Where the retiree looking for a peaceful retreat can connect with the ambitious entrepreneur starting a new chapter. By opening your home’s doors to everyone, you’re helping to build bridges between people from all walks of life. You’re nurturing an environment where friendships bloom, cultures mix, and bonds form that can last a lifetime. Your act as a seller is a brushstroke on the canvas of community, making it more colorful, more harmonious, and more interconnected. Paying It Forward Think back to the moment when you took those exciting first steps toward homeownership – the help, the guidance, the open doors that made it all possible. Now, imagine taking that beautiful circle of support and extending it, giving someone else the chance to take those same heart-pounding steps. It’s like passing the baton in the relay race of life – your willingness to offer a slice of your home’s equity or to explore different financing options can be the game-changer for another dreamer. You’re not just selling a house; you’re creating pathways to aspirations. It’s the ripple effect of kindness; one hand
Hello, homeowners and future home sellers! We’ve started a journey to discover how selling your home can be a life-changing experience, both for you and the hopeful buyers. In part 4, we’re diving into the details and sharing some practical steps to make a real impact in the world of real estate.We know that selling your home is not just a transaction, but a transformation. You’re not only making money, but also making a difference. You’re creating opportunities, supporting the economy, and improving the environment. But how can you do that effectively and efficiently? How can you make sure you get the best deal for your home and for the world? That’s what we’re going to explore in this part. We’re going to give you some tips and tricks on how to prepare your home for sale, how to market it to the right buyers, how to negotiate a fair price, and how to close the deal smoothly. We’re also going to show you some examples of how other homeowners have successfully sold their homes and made a positive impact in their communities. So stay tuned for part 4 of our journey and get ready to learn how to sell your home like a pro and like a hero. Thank you for being part of our journey and our mission to create more happy homes! Setting the Stage Picture this: you’re gearing up to put your beloved home on the market. The thrill of ushering in new beginnings for another family fills you with excitement. But here’s the question – where do you kickstart this journey? Well, it all begins with finding the right wing-person, your real estate agent, the maestro of your home’s symphony. Your journey to make a difference starts with them. You don’t want just any agent; you want a partner in your mission, someone who gets it. You’re searching for that unique individual who understands that inclusivity is not just a buzzword but a powerful force for change. This is the person who believes, just like you, that every step in your home sale can be a step toward a more equitable world. So, the first step is not just any step; it’s finding the perfect partner-in-crime who shares your vision, your values, and your fervor for making a positive impact. Meet and Greet Before you pick your real estate wingman or wingwoman, don’t just go for a name in a hat; go for a heart that understands your mission. It’s not about signing papers and shaking hands; it’s about connecting on a real, human level. So, make that date – schedule a sit-down with your potential agent. Get to know them beyond their business suit. Share your journey, the hurdles you’ve leaped, and the dreams you’re determined to help others reach. Let them in on your secret plan to pay it forward, to make the world a better place, one home sale at a time. Because, my friend, your agent shouldn’t just get your signature; they should get your vision, and be as committed as you are to this mission of inclusivity and change. They should be the kind of real estate sidekick who’s ready to leap into action, armed with a sense of purpose, every step of the way. Dive into Diversity Now, picture this: You’re sitting down with your potential real estate agent, sipping coffee or tea, and having a heart-to-heart about your dreams for your home sale. This meeting is not just about numbers and paperwork; it’s your moment to shine a light on what truly matters to you. You lean in and chat about diversity and inclusivity, sharing your vision of a world where every prospective buyer, no matter their background or financing type, gets a fair shot. You’re not just discussing a transaction; you’re igniting a spark for change. It’s here, in this very conversation, that you set the stage for a real transformation in the real estate world, where everyone gets a fair shake at their own slice of the American dream. Be Open to Creative Financing Alright, here’s another scenario – you’re chatting with your real estate agent, sipping your favorite brew, and you decide to bring up a fantastic idea. You say, “Hey, what do you think about offering a seller credit to help out with those pesky closing costs?” Your agent leans in, and a knowing smile creeps across their face. You see, this move isn’t just practical; it’s a life-saver for many budding homebuyers. It’s like being the superhero in someone else’s home-buying journey, swooping in to rescue them from the clutches of those hefty closing costs. It’s the golden key that can unlock doors to homeownership for those who thought it was just out of reach. So, in essence, this conversation is not just a chat about a financial maneuver; it’s a game-changer, a twist in the plot, and a moment that can truly transform someone’s life. Connect with Your Community Tell your local community that your home is for sale and that you’re looking for someone who needs it. You might be astonished by the support and the leads that can help you find the best buyer. But how do you tell your local community? Well, there are many ways to do that, and we’re going to share some of them with you. Here are some tips on how to spread the word about your home sale and make a positive impression: Use social media. You can post about your home sale on Facebook, Twitter, Instagram, or any other platform that you use regularly. You can also join local groups or pages that are related to real estate, home improvement, or your neighborhood. You can share photos, videos, or stories of your home and why you love it. You can also ask your friends and followers to share your post or tag anyone who might be interested. Create flyers or signs. You can print out flyers or signs that advertise your home sale and
We’ve taken you on a journey through the power of selling your home with inclusivity and open-heartedness. Now, in Part 5, it’s time to share some real stories and case examples that highlight the transformative potential of this approach. We know that selling your home is not just a matter of money, but also a matter of meaning. You’re not only making a profit, but also making a difference. You’re creating opportunities, supporting the economy, and improving the environment. But how does that look like in practice? How can you see the impact of your actions? That’s what we’re going to show you in this part. We’re going to share some stories and examples of how other homeowners have successfully sold their homes with inclusivity and open-heartedness, and how they have changed the lives of others and themselves. We’re going to show you how they prepared their homes for sale, how they marketed them to the right buyers, how they negotiated a fair price, and how they closed the deal smoothly. We’re also going to show you how they celebrated their achievements and moved on to their next adventures. These stories and examples are not only informative, but also inspiring. They will show you that selling your home with inclusivity and open-heartedness is not only possible, but also rewarding. They will show you that you can make a positive difference in the world by selling your home with a generous spirit. They will show you that you can be part of a movement that creates more happy homes. Case 1: The Helping Hand Meet Sarah, a seller who embraced the idea of inclusivity in her home sale. She decided to offer a small seller credit to cover closing costs for a young couple struggling to afford their first home. This simple act of kindness allowed them to achieve their dream of homeownership. The couple, in turn, paid it forward by volunteering in their new community, fostering a culture of goodwill. Case 2: Bridging Generations Tom, an elderly homeowner, found himself in a situation where he needed to sell his family home. He had countless memories in that house and wanted to ensure it went to a buyer who would cherish it as much as he did. By asking for motivation letters, he discovered a young family with kids who had always wanted to live in that neighborhood. The connection between the two families transcended generations, creating a beautiful link between the past and the future. Case 3: A Community of Kindness In a close-knit community, a homeowner named Maria put her house on the market. She spread the word that she was looking for a buyer who shared her values of community, inclusivity, and helping others. In no time, her home found a new family who was passionate about contributing to local charities and supporting neighborhood initiatives. The entire community rallied together, strengthening their bonds through shared values. Case 4: A Beacon of Hope John, a seller with a heart for inclusivity, made it clear to his agent that he wanted to consider all offers, regardless of financing type. He received an offer from a single mother who was struggling to secure a conventional loan. By embracing diversity in the buyer pool, John gave this single mother and her children the chance to escape the cycle of renting and build a stable future. It was a true turning point in their lives. Case 5: The Power of Stories Throughout this journey, we’ve emphasized the importance of motivation letters. One seller, Karen, was deeply moved by the motivation letter from a couple who had been through hardships and were now hoping to provide a stable home for their children. Learning their story not only led to a sale but also to a long-lasting friendship between the two families, who now celebrate life’s milestones together. These real stories demonstrate the incredible impact that a seller can have on the lives of buyers and the community. By embracing inclusivity, open-heartedness, and a willingness to pay it forward, homeowners like Sarah, Tom, Maria, John, and Karen have become beacons of hope and catalysts for positive change. In closing, as you contemplate selling your home, remember that every decision you make can lead to extraordinary transformations. Your home sale can create a ripple effect of kindness and inclusivity that reaches far beyond the transaction itself. Thank you for joining us on this journey. May your future home sale be a testament to the power of open hearts and open doors.
$10 a month, or $84 a year.
Become a member Member sign in