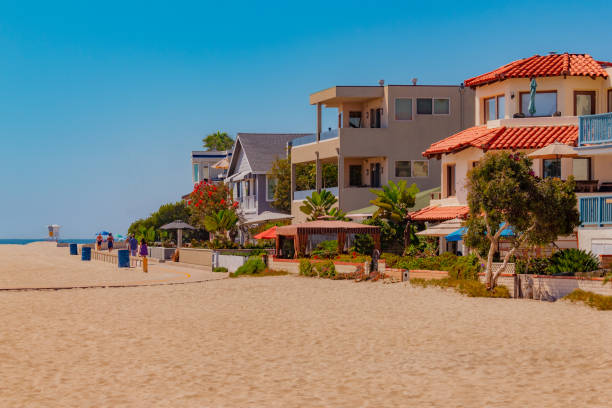
San Diego County’s coastline has long carried a premium, defined by limited land, strong demand, and a lifestyle that continues to attract high-income buyers. In 2026, that premium has reached a point where affordability is no longer just a pricing issue—it has become a qualification barrier. The challenge is no longer simply whether a home is expensive, but whether buyers can meet the financial thresholds required to secure financing in a high-rate environment.
Median home prices across coastal communities such as La Jolla, Del Mar, and Encinitas now exceed $1.8 million, with many properties trading well above $2.5 million. At the same time, mortgage rates have stabilized between 6.5% and 7%, significantly increasing the cost of borrowing compared to the sub-3% environment seen just a few years ago.
This shift has created a widening gap between household incomes and mortgage qualification requirements. Buyers who might have qualified in 2021 are now priced out not because of listing prices alone, but because financing standards have tightened relative to income. The result is a housing market where eligibility itself has become the primary constraint.
The True Cost of Coastal Ownership
To understand the scale of the challenge, it is necessary to break down the financial requirements for purchasing a typical coastal home in San Diego County. With a median coastal price of approximately $1.9 million, a buyer putting down 20%—roughly $380,000—would need to finance about $1.52 million.
At a 6.75% interest rate on a 30-year fixed mortgage, the monthly principal and interest payment alone would reach approximately $9,850. When property taxes are added, at an average rate of 1.1%, the annual tax burden comes to about $20,900, or $1,740 per month. Insurance and maintenance costs can conservatively add another $600 to $800 monthly, bringing the total housing cost to nearly $12,400 per month.
Lenders typically require that housing costs do not exceed 28% to 31% of a borrower’s gross monthly income. Using a 30% benchmark, a buyer would need to earn approximately $41,300 per month, or just under $500,000 annually, to comfortably qualify for this property.
This figure places coastal homeownership far beyond the reach of the typical San Diego household. The county’s median household income sits near $95,000, meaning the income required for coastal ownership is more than five times the median. Even dual-income households earning a combined $200,000 fall significantly short of qualifying thresholds.
Mortgage Rates and the Redefinition of Eligibility
The current affordability crisis is not driven by home prices alone. Mortgage rates have fundamentally altered the qualification landscape. A comparison illustrates the magnitude of this shift.
In 2021, a $1.52 million loan at a 3% interest rate would have resulted in a monthly payment of approximately $6,400. At that level, the required annual income to meet a 30% debt-to-income ratio would have been around $256,000.
By 2026, the same loan at 6.75% increases the monthly payment by over $3,400, raising the required income by nearly $240,000. This represents a 93% increase in income required to qualify for the same property, without any change in price.
Debt-to-income ratios further complicate eligibility. Many borrowers carry additional obligations, including student loans, auto loans, and credit card balances. Lenders often cap total debt obligations at 43% to 45% of gross income. For a buyer already allocating $12,400 monthly to housing, even modest additional debts can push them beyond allowable limits, disqualifying them entirely.
As a result, qualification is increasingly limited to high-net-worth individuals, executives, and buyers with significant liquidity. Cash buyers have also become more prominent in coastal transactions, accounting for an estimated 28% to 32% of sales in certain high-end submarkets.
A Market Defined by Exclusion
The consequences of this financing reality are visible across San Diego County’s housing market. Coastal areas continue to command strong prices, but transaction volume has become more selective. In 2025, sales in the $2 million-plus segment declined by approximately 7%, even as prices remained stable or increased slightly.
Meanwhile, the pool of eligible buyers has narrowed sharply. First-time buyers are effectively absent from coastal markets, while move-up buyers face significant barriers due to the cost of trading up into higher-rate mortgages. Many homeowners who secured low-interest loans between 2020 and 2022 are choosing to stay in place rather than re-enter the market at current rates, further reducing supply.
This dynamic has created a bifurcated market. Coastal properties remain expensive and relatively stable, but accessibility has diminished to a small segment of the population. Inland markets, while more affordable, are experiencing their own pressures as displaced demand shifts away from the coast.
Affordability as a Qualification Crisis
Framing the issue as a pricing problem alone misses the core challenge. Even if coastal home prices were to decline by 10%, the impact on affordability would be limited. A $1.9 million home dropping to $1.71 million would still require a loan exceeding $1.36 million, resulting in monthly payments above $8,800 at current rates. The required income would remain well above $400,000 annually.
This highlights a critical point: affordability in 2026 is driven as much by financing conditions as by property values. Mortgage rates, underwriting standards, and income thresholds are now the primary determinants of market access.
Without a significant decline in interest rates or a substantial increase in incomes, the gap between qualification requirements and household earnings is unlikely to close. This suggests that the current affordability constraints are not temporary but structural.
San Diego County’s coastal housing market illustrates a broader shift taking place across high-cost regions. Homeownership is no longer defined solely by the ability to meet a purchase price; it is defined by the ability to qualify under increasingly demanding financial conditions.
With required incomes approaching $500,000 for typical coastal properties, the market has effectively moved beyond the reach of even well-compensated professionals. Mortgage rates have amplified this divide, turning affordability into a question of eligibility rather than aspiration.
Until financing conditions ease or incomes rise significantly, coastal homeownership will remain concentrated among a narrow group of buyers. For the broader market, the challenge is not just rising prices—it is a qualification threshold that continues to move further out of reach.
Eric Lawrence Frazier Advisory Services Research Team
Thank you for taking the time to read and reflect. I write to help people think clearly about money, business, real estate, and life — not from theory, but from decades of lived experience.
If you are navigating a financial decision, building a business, considering homeownership, or simply trying to make better use of your time and resources, I invite you to engage further.
Subscribe to The Power Is Now TV to connect with me live every weekday, Monday through Friday, from 10:00 AM to 11:00 AM PST, as we record television shows across the Power Is Now TV Network. As a subscriber, you can participate in live tapings, engage in real-time discussions, and connect directly with industry leaders.
Visit ThePowerIsNow.com to access real estate magazines, books, podcasts, television shows, and exclusive media content focused on homeownership, business, and wealth-building.
For personalized support, consulting, and advisory services in real estate, mortgages, business, and personal finance, visit EricFrazier.com to schedule a consultation and learn more about my work as your trusted advisor in business and wealth.
Eric Lawrence Frazier, MBA
Your trusted advisor in business and wealth
www.ericfrazier.com | www.thepowerisnow.com
NMLS #461807 | CA DRE #01143484
Schedule a consultation: https://calendly.com/ericfrazier/real-estate-mortgage-consultation-clients
References
Federal Reserve Bank of St. Louis. (2026). 30-Year Fixed Mortgage Rate Data. Retrieved from https://fred.stlouisfed.org
U.S. Census Bureau. (2026). Income and Demographic Data for San Diego County. Retrieved from https://www.census.gov
California Department of Finance. (2026). Housing Market and Price Data for California Counties. Retrieved from https://dof.ca.gov