Homeownership Part 7: Community Land Trusts: The Quiet Model That Actually Works
Every conversation about the housing affordability crisis eventually arrives at the same impasse. Home prices are too high. Wages haven’t kept up. Down payments are out of reach. Mortgage rates are elevated. Supply is short. The problems are well-documented, endlessly discussed, and, from the perspective of most aspiring homeowners, maddeningly resistant to solution. What rarely gets discussed with the same urgency is the question of whether the standard model of homeownership itself, the one where a buyer purchases land and structure together at full market price, is the only model worth pursuing. It isn’t. And the alternative that has been quietly demonstrating results for decades deserves far more attention than it typically gets. Community Land Trusts — CLTs — are nonprofit organizations that permanently remove land from the speculative market, hold it in trust for the benefit of a community, and sell the homes sitting on that land to income-eligible buyers at prices that reflect the cost of the structure rather than the full market value of the combined property. The buyer owns the home. The CLT owns the land. The result is a purchase price that is often dramatically more affordable than anything available on the open market, and a model of ownership that has proven more stable, more equitable, and more durable than conventional homeownership in almost every metric that matters. Where the model came from The origins of the CLT model in the United States are rooted directly in the civil rights movement. The first modern CLT in the United States was established in Albany, Georgia, in 1969 by Robert Swann and Slater King. Born out of the civil rights movement, the New Communities land trust consisted of more than 5,000 acres of farmland where African-American families, many of them poor farmers from the South, could affordably access, build on, and farm land at a time when the community faced significant obstacles to land ownership and financing. The CLT was not designed as an idealistic experiment or a fringe alternative to mainstream homeownership. It was a practical response to a specific and urgent problem: a community that was systematically excluded from conventional land ownership needed a model that could work around those exclusions while building long-term stability. That founding purpose, advancing racial equity and community stability in the face of a market that was working against marginalized communities, remains central to the CLT movement today. There are now hundreds of active community land trusts operating across the United States, with steady growth over the past decade. The expansion is not concentrated in places where housing is traditionally cheapest. It is happening in regions where affordability has become increasingly strained, pushing policymakers and communities to explore structural alternatives. How it actually works The mechanics of the CLT model are straightforward, even if they require a shift in how most people think about property ownership. When a buyer purchases a CLT home, they pay only for the structure, the actual building, at a subsidized price that reflects their income and the CLT’s affordability mission. The land beneath the home is leased to the buyer through a long-term ground lease, typically renewable every 99 years, at a modest monthly fee. Because the purchase price is substantially lower, the mortgage is smaller, and the monthly payment is more manageable, often significantly so, even in markets where standard homeownership is completely out of reach for moderate-income earners. The buyer builds equity in the home as they pay down the mortgage, and they are entitled to a share of any appreciation in the home’s value when they sell. The share is defined by a resale formula that varies across CLTs, but is generally designed to allow the homeowner to capture a fair return on their investment while ensuring the home remains affordable for the next buyer. Homeowners build wealth in two ways: through the forced savings of paying down mortgage principal, and through the share of appreciation allocated under the resale formula. The equity accumulated is more modest than in market-rate ownership, but it is real, stable, and insulated from extreme market volatility. The strict formulas CLTs use to calculate resale values effectively remove these properties from speculative market swings, providing protection during downturns while preserving long-term affordability. The stepping stone most people don’t know about Perhaps the most compelling feature of the CLT model is what happens after ownership. While often framed as a permanent alternative to market-rate housing, in practice it frequently functions as a stepping stone. A significant share of CLT homeowners eventually transition into market-rate ownership. The CLT provides an entry point into homeownership that would otherwise be inaccessible, allowing buyers to build credit history, accumulate savings, and establish equity. That foundation can then be leveraged into conventional housing opportunities that were previously out of reach. In many cases, initial investments required to enter CLT ownership are relatively small compared to traditional down payments, and the equity gained over time, though modest, becomes meaningful when applied toward a later purchase. For many households, the CLT is less an endpoint than a bridge into broader housing stability. What the data shows about stability Beyond affordability, CLTs demonstrate strong performance in housing stability. Homeowners in CLTs are significantly less likely to experience foreclosure or delinquency during market downturns compared to conventional homeowners in similar income brackets. This resilience is not accidental. CLTs typically provide pre-purchase education, structured underwriting, and ongoing support to homeowners after purchase. This relationship-based model allows early intervention when financial stress emerges, preventing issues from escalating into default. During the 2008 housing crisis, CLT homeowners experienced far lower foreclosure rates than the broader market. The model’s combination of affordability, education, and ongoing stewardship created a buffer against the shocks that destabilized conventional homeownership. Research also indicates that CLTs contribute to neighborhood stability. Rather than depressing surrounding property values, CLTs often help stabilize or even increase nearby home prices by reducing vacancy, preventing distress sales, and maintaining long-term affordability in areas under pressure from speculation. The growth that
The First Keepers of the Claim: Hiram Revels, Joseph Rainey, and the Black Men Who Entered Congress While Slavery Was Still Breathing – Footnotes
United States Senate, “Hiram Revels: First African American Senator.” The Senate states that Hiram Revels of Mississippi became the first African American member of the U.S. Senate and took the oath on February 25, 1870. https://www.senate.gov/artandhistory/senate-stories/First-African-American-Senator.html U.S. House of Representatives, History, Art & Archives, “Representative Joseph Rainey of South Carolina, the First African American to Serve in the House.” The House identifies Joseph Rainey as the first African American member of the U.S. House of Representatives and notes that Rainey and his parents were enslaved before his father purchased the family’s freedom. https://history.house.gov/Historical-Highlights/1800-1850/Representative-Joseph-Rainey-of-South-Carolina%2C-the-first-African-American-to-serve-in-the-House/ United States Senate, “The District of Columbia Compensated Emancipation Act.” The Senate records that the 1862 act freed enslaved people in Washington, D.C., and compensated owners up to $300 for each freed person. https://www.senate.gov/artandhistory/history/common/civil_war/DCEmancipationAct_FeaturedDoc.html National Archives, “The Freedmen’s Bureau.” The National Archives states that the Bureau of Refugees, Freedmen, and Abandoned Lands was established by Congress on March 3, 1865, and was responsible for matters relating to refugees, freedmen, and abandoned or seized lands. https://www.archives.gov/research/african-americans/freedmens-bureau
The First Keepers of the Claim: Hiram Revels, Joseph Rainey, and the Black Men Who Entered Congress While Slavery Was Still Breathing – Poem
The First Keepers of the Claim Five years from chains to chamber doors, They stood where power lied, With freedom raw upon their backs, And blood still in the tide. The war was done, the smoke remained, The oath was not the same, For men once counted under chains Now entered in their name. Freedom came, but debt remained, Justice bowed, but debt remained, Flags were raised, but debt remained, Names were changed, but debt remained. They fought for schools, for votes, for law, For breath beneath the night, While hatred changed its coat and tie And called itself the right. The land was promised, then returned To hands that held the whip, The slaveholder found the treasury, The freedman lost his grip. Freedom came, but debt remained, Justice bowed, but debt remained, Flags were raised, but debt remained, Names were changed, but debt remained.They paid the hand that held the chain, They left the wounded with the pain, They dressed betrayal up as gain, They called it peace and kept the stain. Freedom came, but debt remained, Justice bowed, but debt remained, Flags were raised, but debt remained, Names were changed, but debt remained. Eric Lawrence Frazier Poet
The First Keepers of the Claim: Hiram Revels, Joseph Rainey, and the Black Men Who Entered Congress While Slavery Was Still Breathing
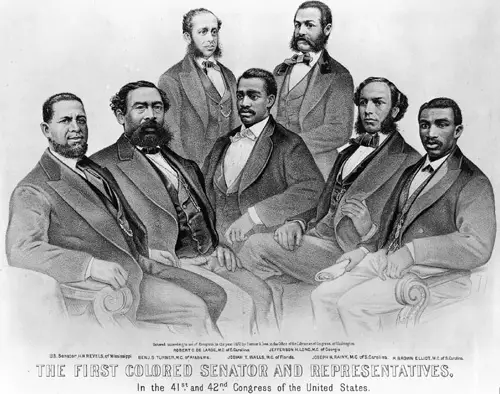
Juneteenth is not merely a celebration of freedom. It is the record of freedom delayed, freedom withheld, freedom announced only after power had been forced to surrender what it never had the moral right to possess. That is why Juneteenth and reparations cannot be separated. One remembers the announcement. The other demands the settlement. In 1865, the legal institution of slavery was defeated. By 1870, Hiram Rhodes Revels of Mississippi stood in the United States Senate as the first African American senator, and Joseph Hayne Rainey of South Carolina stood in the House of Representatives as the first African American member of that chamber. Five years after emancipation, Black men entered the Congress of the United States. Not fifty years. Not a century. Five years. Men born under or near the shadow of slavery stood in the rooms of federal power representing a people this nation had bought, sold, whipped, hunted, counted, taxed, excluded, and exploited. Their presence was not decoration. Their presence was evidence. America did not send them into a healed republic. America sent them into a republic still contaminated by the same Confederate spirit that had just lost the war and was already preparing to win the aftermath. The battlefield had changed, but the philosophy had not died. Slavery had fallen as law, but white domination immediately began searching for new instruments: Black Codes, racial terror, voter suppression, land restoration to former Confederates, convict leasing, segregated education, and the slow suffocation of Reconstruction. The nation that had been forced to release Black bodies still had no intention of repairing Black lives. Revels and Rainey were not modern reparations legislators. They were the first federal witnesses of Black citizenship after slavery. Their fight was survival. Their fight was protection. Their fight was education, voting rights, federal enforcement, and the right of Black people to exist as political beings in a country that had spent centuries denying their humanity. Before Black America could demand payment, Black America had to survive the campaign to make freedom meaningless. That is the first truth of the reparations claim. The claim did not begin with a check. It began with survival. It began with Black people insisting that emancipation was not enough if the nation returned them to the mercy of the same people who had enslaved them. It began with the understanding that freedom without land, wages, safety, schools, credit, and federal protection was freedom left exposed in the street. The federal government understood compensation. That must be stated without apology. The United States knew how to calculate loss when the claimant was the enslaver. In 1862, when slavery was abolished in Washington, D.C., the federal government compensated loyal slaveholders up to $300 for each freed person. The money went not to the enslaved, but to those who had claimed ownership over them. America did not find compensation radical when the person being compensated was the one who had profited from bondage. Compensation became controversial only when the moral logic pointed toward the enslaved. The Freedmen’s Bureau, created in 1865, also reveals what the government knew. The Bureau was established to aid formerly enslaved people and manage abandoned or confiscated lands. The government knew land mattered. It knew property mattered. It knew that emancipation without economic foundation would leave millions of Black people vulnerable to dependency, violence, and exploitation. Then the promise was betrayed. Land was restored to former Confederates, and the formerly enslaved were left to build lives in a country that had taken everything from them and then acted offended when they asked for anything back. That betrayal is the soil from which every later reparations demand grows. Black people were not asking for charity. They were asking for the unpaid portion of freedom. They were asking for the economic substance that should have followed legal emancipation. They were asking for what the federal government had already proven it could provide when it cared to provide it: recognition, administration, calculation, and compensation. The tragedy of Reconstruction is not that Black people failed. Black people organized, voted, held office, built schools, formed communities, purchased land where possible, and entered public life with a courage that should shame every generation that now treats democracy as an occasional errand. Reconstruction failed because America allowed white power to regroup. It failed because the federal government withdrew protection before justice had taken root. It failed because the nation preferred reconciliation with former Confederates over restitution for formerly enslaved people. Hiram Revels and Joseph Rainey stand at the beginning of this series because they represent the first keepers of the claim. They did not carry H.R. 40. They carried something more primitive and more dangerous to white power: the visible contradiction of Black citizenship in a nation built on Black enslavement. They stood in Congress before America had decided whether emancipation would mean a new social order or merely a rearranged plantation. John Conyers would come more than a century later and give the claim a bill number. Sheila Jackson Lee and Ayanna Pressley would carry it into another generation. Barack Obama would stand inside the highest office in the land and still leave the claim untouched. But Revels and Rainey came first. Their presence in Congress was the beginning of the federal record. They proved that Black people had survived slavery. Their era proved that survival was not repair. Juneteenth announces freedom delayed. Reconstruction reveals repair denied. The first Black men in Congress carried the testimony of a people who had been legally emancipated but economically abandoned. America changed the legal status of Black people, then refused to settle the account. That refusal is the beginning of the debt. Thank you for taking the time to read and reflect. I write to help people think clearly about money, business, real estate, and life — not from theory, but from decades of lived experience. If you are navigating a financial decision, building a business, considering homeownership, or simply trying to make better use of your
High-Income Markets Under Pressure—Are Orange County Buyers Overleveraged in 2026?
Orange County has long been viewed as one of California’s most stable and desirable housing markets. With its coastal cities, strong school districts, and high household incomes, it has consistently attracted professionals, business owners, and long-term investors. However, beneath the surface of this premium market, financial pressure is beginning to build in ways that are less visible but increasingly significant. Over the past few years, home prices in Orange County have continued to climb, even as interest rates have remained elevated. Median home prices now regularly exceed $1.1 million, while monthly mortgage payments for new buyers often range between $5,500 and $7,500 depending on down payment size and loan structure. At the same time, wage growth has not kept pace with housing costs, creating a widening gap between income and affordability. This imbalance raises an important question: are buyers in Orange County becoming overleveraged in 2026? Understanding how financing conditions, debt ratios, and market behavior are evolving provides critical insight into the sustainability of one of California’s most competitive housing markets. This article examines current affordability pressures, financing trends, and the financial risks shaping buyer behavior across the county. Rising Home Prices and Affordability Strain Orange County remains one of the most expensive housing markets in the United States. As of 2025–2026, the median home price sits between $1.05 million and $1.2 million, depending on the data source and submarket. Coastal cities such as Newport Beach, Laguna Beach, and Huntington Beach regularly exceed $1.5 million for single-family homes, with luxury properties far surpassing that range. Even inland cities like Irvine, Tustin, and Anaheim have seen significant appreciation over the past decade. Irvine, for example, now frequently records median prices above $1.3 million for detached homes. This sustained price growth has outpaced household income increases, which have grown at a much slower rate of approximately 3% to 4% annually. As a result, affordability has become increasingly constrained. A household earning $200,000 annually—which is considered high income in most parts of the country—now often qualifies for only a mid-tier home in Orange County, depending on debt levels and down payment capacity. Financing Pressures and Debt-to-Income Ratios One of the most important indicators of buyer stress in Orange County is the debt-to-income (DTI) ratio. Lenders typically prefer a DTI below 43%, but many buyers in the region are stretching close to or above this threshold due to high monthly housing costs. With interest rates hovering between 6% and 7% for much of 2025, monthly mortgage payments have increased significantly compared to the ultra-low rate environment of 2020–2021. A home purchased at $1.1 million with 20% down can result in monthly payments exceeding $6,000, excluding taxes, insurance, and HOA fees. In higher-end communities, total monthly housing costs can exceed $8,000. This has led to a noticeable shift in buyer behavior. Many households are increasing down payments using savings or equity from previous homes. Others are relying on dual-income structures or financial assistance from family members to qualify for loans. While this allows transactions to continue, it also increases household financial exposure. Market Behavior: Stretching for Entry Despite affordability challenges, demand in Orange County remains strong. Inventory levels remain relatively low, with months of supply often ranging between 2.5 and 3.5 months—well below a balanced market. This limited inventory continues to support high prices, even in the face of affordability concerns. However, the composition of buyers has changed. There is a growing share of “rate-sensitive” buyers who are purchasing at the upper limit of their financial capacity. Many are prioritizing location over financial flexibility, choosing to enter the market now rather than waiting for potential price adjustments. This behavior has created a market where homes are still selling, but buyers are increasingly leveraged. While default rates remain low, the financial cushion for many households has narrowed compared to previous years. The Role of Wealth Concentration Orange County’s housing market is also influenced by significant wealth concentration. High-income industries such as technology, healthcare, finance, and professional services support a strong base of cash-heavy buyers. In many luxury transactions, buyers are either making large down payments or purchasing outright without financing. This segment of the market helps stabilize prices, particularly in coastal and luxury neighborhoods. However, it also creates a two-tier market: one driven by liquidity and wealth, and another heavily dependent on financing conditions. As interest rates remain elevated, the gap between these two segments has widened. Cash buyers continue to transact with little sensitivity to rates, while financed buyers face increasing constraints. Risks of Overleveraging in the Current Cycle The concern around overleveraging does not necessarily point to an immediate market correction, but rather to increased vulnerability. When households allocate a larger portion of income toward housing costs, they become more sensitive to economic shifts such as job loss, interest rate fluctuations, or unexpected expenses. In Orange County, where many buyers are committing a significant share of income to mortgage payments, financial flexibility is more limited than in previous cycles. While foreclosure rates remain historically low, rising household debt levels suggest that some buyers are operating with reduced financial buffers. Additionally, property taxes, insurance premiums, and maintenance costs continue to rise, further increasing total housing expenses. These factors compound the strain on leveraged households. Orange County remains one of California’s most desirable and resilient real estate markets, supported by strong incomes, limited supply, and long-term demand. However, beneath this stability, financial pressure is building among a growing segment of buyers. Elevated home prices, higher interest rates, and stagnant affordability have led many households to stretch their financial capacity in order to enter the market. While this does not signal immediate instability, it does highlight a shift in buyer behavior. The market is increasingly defined by financial commitment at the upper limits of affordability rather than broad-based accessibility. Understanding this dynamic is essential for evaluating both short-term risks and long-term sustainability in Orange County’s housing landscape. Thank you for taking the time to read and reflect. I write to help people think clearly about money,
Homeownership Part 6: Your Home Is Worth Less Because of Who You Are
Imagine spending months saving for a down payment, navigating a competitive market, securing a mortgage, and finally closing on a home you are proud of. Imagine investing tens of thousands of dollars in renovations over the years, watching the neighborhood around you appreciate, and then calling an appraiser to refinance at a better rate, only to be handed a valuation that bears almost no relationship to what comparable homes in the area are actually worth. Imagine suspecting that the number is low because of your race. Imagine having that suspicion confirmed. This is not a hypothetical. It is the documented, tested, and financially quantified reality of what appraisal bias does to Black homeowners across the United States, and it is happening right now, inside a system that has yet to be fundamentally reformed. What the research actually shows The data on appraisal bias has accumulated steadily over the past several years to a point where its existence is no longer seriously disputed by credible researchers. What remains contested is the scale of its contribution to the broader devaluation of homes in Black neighborhoods, a distinction that matters for policy, but does not change the central finding that the bias is real, documented, and costly. Brookings Institution research found that homes in Black neighborhoods are valued roughly 21% to 23% below what their valuations would be in non-Black neighborhoods. Appraisal bias explains approximately 9% to 19% of that devaluation, depending on modeling approaches. Appraisal transactions in majority-Black neighborhoods are significantly more likely to be appraised under the contract price than homes in majority-white neighborhoods. At the neighborhood level, the cost of devaluation across major metro areas amounts to roughly $162 billion. That is not a rounding error in the housing market. It is a massive drain on Black wealth, accumulated over years of a system that routinely assigns lower values to the same physical structures based on who lives in them and where they are located. Even when Black Americans do own homes, their median home value sits significantly below the national median. That gap does not exist because Black homeowners are purchasing inferior properties or maintaining them less carefully. It exists because the mechanism used to establish home values has built into it a set of assumptions and practices that consistently produce lower numbers for homes in Black communities. Lower appraisals mean lower equity. Lower equity means less borrowing power, less capacity to fund home improvements, less collateral for other financial goals, and ultimately less wealth to pass on, in a country where home equity is the cornerstone of middle-class financial stability. The methodology that makes bias possible Understanding how appraisal bias works requires understanding how appraisals work. The dominant methodology in residential real estate valuation is the sales comparison approach, where an appraiser determines a home’s value primarily by comparing it to recent sales of similar properties in the same area. The approach sounds neutral, and in theory it is meant to be. In practice, it encodes historical inequities directly into current valuations. The origins of appraisal bias date back to the 1930s, when federal housing policy classified predominantly Black neighborhoods as high risk. Those classifications shaped lending access, investment patterns, and long-term property values. When comparable sales in a neighborhood reflect decades of disinvestment and depressed property values, any appraisal methodology that relies heavily on those comparables will reproduce those lower numbers in perpetuity. The bias does not need to be conscious or intentional to be structural. The system can produce racially unequal outcomes through processes that appear entirely objective on their face. An additional structural factor is the composition of the appraisal workforce itself. The profession remains overwhelmingly white, with Black appraisers representing a very small share of the field. A system this homogeneous, applying discretionary judgment in a process that directly affects the wealth of communities of color, is not well-positioned to consistently identify or correct bias. Research shows that lower appraised values for Black-owned homes persist even after controlling for a wide range of variables and individual appraiser effects. The pattern is not confined to a few actors. It is systemic. The families who proved it Some of the most compelling evidence of appraisal bias comes from homeowners who tested it directly. In multiple documented cases, families received low appraisals, removed visible indicators of race from their homes, and had a different person present the property for a second appraisal. In those instances, valuations increased significantly, in some cases by more than 40%. Other investigations have produced similar findings. Controlled testing has shown that homes associated with Black ownership are consistently valued lower than identical homes presented under white ownership conditions. These results are not statistical abstractions. They are real transactions, with real financial consequences, demonstrating how perception can directly influence valuation outcomes. A reform effort that was dismantled Federal efforts to address appraisal bias gained momentum in the early 2020s through interagency initiatives aimed at improving transparency and accountability in valuation practices. These efforts sought to standardize data collection, create mechanisms for challenging valuations, and examine structural inequities in the appraisal process. In 2025, those initiatives were effectively discontinued, halting much of the federal coordination that had been underway. The policy shift did not eliminate the underlying issue. It removed the primary federal structure tasked with studying and addressing it. In response, new legislation has been introduced to modernize appraisal practices, increase transparency in valuation data, and give homeowners a formal mechanism to appeal potentially biased appraisals. These proposals represent incremental progress, but they stop short of addressing the full structural depth of the problem. What is actually at stake It is important to be precise about what appraisal bias represents. It is not about isolated misconduct, nor is it about occasional error. It is a documented pattern in which the same property yields different valuations depending on the racial context in which it is appraised. Over time, across millions of transactions, those differences accumulate into measurable disparities in household wealth. As one
Homeownership Part 5: The 30-Point Gap That Won’t Move
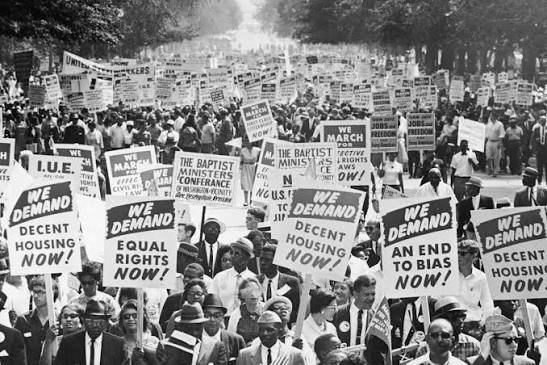
In 1968, Congress passed the Fair Housing Act. It was a landmark moment, a formal, legal declaration that discriminating against someone in the sale, rental, or financing of a home on the basis of race was no longer acceptable in the United States. After decades of codified exclusion, after redlining and restrictive covenants and a housing market built around segregation, the law drew a line and said: no more. More than fifty years later, the gap between white and Black homeownership rates is wider than it was when that law was signed. That sentence deserves to be read slowly. Not slightly larger. Not roughly equivalent. Wider. In 1968, the gap between white and Black homeownership was 27 percentage points. By 2026, that gap has grown to 28.4 points. White homeownership sits at around 71.6%, while Black homeownership stands at just 43.2%. Half a century of civil rights legislation, fair lending enforcement, community reinvestment initiatives, and targeted homeownership programs, and the needle has not just failed to close the gap, it has moved in the wrong direction. That is not a minor policy failure. It is one of the most significant and underacknowledged indictments of American housing policy in the modern era. What the numbers represent beyond percentages Numbers like these are easy to encounter and difficult to absorb. A 28-point gap in homeownership rates is not simply a statistical imbalance. It represents a compounding shortfall in wealth, stability, and opportunity that reproduces itself across generations with remarkable persistence and force. Homeownership remains the cornerstone of wealth in America, accounting for roughly 68% of total household net worth for the average family. When that pathway is obstructed, it does not just limit where one can live, it defines how one’s children will live. According to the Federal Reserve’s 2024 Survey of Consumer Finances, the median net worth of white families exceeds $285,000, compared to just $45,000 for Black families. That six-to-one wealth disparity is not explained by differences in effort, intelligence, or aspiration. It is the compounded financial residue of generations systematically denied access to the primary wealth-building vehicle that American society has made available to its citizens. The overall Black homeownership rate slipped to 43.9% in mid-2025, while the white rate hovered around 74%. Redfin chief economist Daryl Fairweather noted that Black millennials and Gen Zers are bearing the brunt of the racial homeownership gap because since they have reached homebuying age, the country has faced significant financial challenges and a major housing supply shortage. The young people who should be driving new Black homeownership growth are entering the market at a moment of maximum difficulty, high prices, elevated mortgage rates, scarce inventory, with less generational wealth to draw on and more systemic friction to navigate than their white counterparts of the same age. How the gap was built To understand why the gap persists, you have to understand how it was constructed, not as an accident or a byproduct of neutral market forces, but as the deliberate result of government policy and private practice working in coordination over several decades. Redlining is the most well-known mechanism. Starting in the 1930s, the Home Owners’ Loan Corporation systematically graded neighborhoods across the country, labeling communities with significant Black populations as “hazardous” and marking them in red on maps that banks and mortgage lenders used to determine where they would and would not extend credit. The effect was to starve entire neighborhoods of mortgage capital, making it nearly impossible for Black families to buy in those areas and equally difficult to sell, since no buyer could obtain financing. Property values in those communities stagnated, investment dried up, and infrastructure deteriorated, not because of anything the residents did, but because federal policy had made their neighborhoods financially untouchable. The GI Bill, often celebrated as one of the most transformative pieces of social legislation in American history, extended these inequities rather than correcting them. Though the bill helped white Americans prosper and accumulate wealth in the postwar years, it did not deliver on that promise for Black veterans who had served in segregated ranks. The GI Bill relied on the same redlined maps to determine where mortgages could be insured and offered. In Mississippi, a survey of 13 cities found that only 2 of the 3,229 VA loans issued in 1947 went to Black homebuyers. The largest federally subsidized wealth transfer in American history, the creation of the postwar middle class through suburban homeownership, was administered almost exclusively to white families. The long-term consequences of that exclusion are still being lived. What this created was a structural divergence that has proven extraordinarily difficult to reverse. White families who bought homes in the 1940s and 1950s, often with federal assistance, in newly constructed suburbs with good schools and appreciating property values, passed equity, security, and down payment capacity to their children and grandchildren. Black families who were denied that same access passed forward the absence of it. The gap in homeownership today is not merely a reflection of current market conditions. It is the balance sheet of a debt that has never been paid. The barriers operating right now If the historical exclusions had simply stopped without any ongoing structural disadvantages, the gap might have closed on its own over time. But the barriers to Black homeownership did not end with the Fair Housing Act. They evolved, adapted, and in some cases intensified. Mortgage denial rates remain starkly unequal. According to the National Association of Realtors’ 2025 Snapshot of Race and Home Buying, Black mortgage applicants face a denial rate of 21% and Hispanic applicants face a denial rate of 17%, compared to just 11% for white applicants and 9% for Asian applicants. These are not differences explained by creditworthiness alone. Research consistently finds that racial disparities in mortgage denial persist even after controlling for income, credit score, and loan-to-value ratio. The system is producing unequal outcomes for equal applicants, and the downstream consequences for homeownership accumulate year after year. Appraisal bias is another
Homeownership Part 4: The Insurance Crisis Nobody Is Connecting to the Housing Crisis
When people talk about what’s making homeownership unaffordable in America, the conversation almost always lands on the same handful of explanations: home prices, mortgage rates, down payments, and housing supply. Those are real problems, each worthy of serious attention. But there is another force working quietly against both aspiring and existing homeowners that rarely makes it into that conversation, one that can block a purchase before it starts, destabilize a mortgage that was already being paid faithfully, and in the worst cases, trigger the loss of a home that a family worked for years to keep. That force is the home insurance crisis. And it is far more connected to the housing affordability problem than most coverage of either subject acknowledges. A market in serious trouble The numbers describing the state of home insurance in America are striking, and they’ve moved fast. Homeowners insurance premiums rose by 64% nationwide between 2021 and 2025, nearly four times more than they did in the previous five-year period. That is not a modest adjustment to reflect changing costs. That is a fundamental repricing of what it costs to protect a home, happening in a compressed window of time that has left millions of homeowners scrambling to absorb increases they did not budget for and often cannot avoid. The premium spike is only part of the story. A recent survey of home buyers and sellers found that nearly half of respondents encountered issues with home insurance during a transaction, while 21% reported that a deal fell through entirely because of it. In states like Louisiana, 30 to 40% of mortgage loans fail because of high home insurance costs. These are not edge cases or regional anomalies. These are mainstream, widespread market failures affecting buyers and sellers across the country, deals collapsing not because of credit problems or appraisal disputes, but because the insurance required to close simply cannot be obtained at a price the transaction can bear. The mechanism connecting insurance to the purchase process is often misunderstood, but it is direct and unforgiving. While the 30-year fixed-rate mortgage has traditionally given homeowners stable and predictable payments, this stability is now being undermined. As premiums surge, mortgage payments, which in most cases include insurance through escrow, become increasingly less affordable and more unpredictable for millions of homeowners. A buyer who qualifies for a mortgage based on projected monthly costs can find themselves priced out of their own purchase when the insurance quote comes back significantly higher than anticipated. The mortgage math clears. The insurance math doesn’t. The deal dies. From pricing crisis to coverage crisis The problem has moved beyond cost alone into something harder to solve, availability. In an increasing number of markets across the country, private insurers are not simply charging more, they are leaving. Insurers facing higher risk profiles are cutting coverage, refusing renewals, or restructuring their policies in ways that shift risk onto homeowners. Those left without coverage, or forced to rely on state insurers of last resort, end up with the most to lose when a natural disaster strikes. After the devastating California wildfires, it was revealed that many of those affected had their policies canceled by their insurer only months before the disaster. The state-backed insurers of last resort that step in when private markets retreat are not a comfortable backstop. They are expensive, limited in what they cover, and were never designed to absorb the volume of policyholders now depending on them. Excess and surplus lines policies, which typically come with higher premiums and fewer consumer protections, have emerged as coverage options for properties that private insurers will no longer touch. In California, Florida, and Texas, these products accounted for roughly 16% of policies by December 2025, up from under 2% in 2023. In the span of two years, a significant portion of homeowners in three of the country’s largest states shifted from standard private coverage to a less protected, more expensive alternative, not by choice, but by necessity. The force-placed insurance trap One of the least discussed mechanisms by which insurance costs can destabilize a homeowner’s financial situation is force-placed insurance, sometimes called lender-placed insurance. Most homeowners have never heard of it until it happens to them, and by then, the financial damage has often already begun. When a homeowner’s insurance policy lapses, whether because a premium went unpaid, a policy was canceled by the insurer, or coverage was deemed insufficient, the mortgage lender is legally required to protect its financial interest in the property. The lender steps in with a force-placed insurance policy, pays the premium upfront, and then adds the cost to the borrower’s monthly mortgage payment. If the borrower cannot pay, the lender can initiate foreclosure proceedings. The homeowner does not choose this policy, does not select the insurer, and has no ability to shop for a better rate. The lender picks the company and passes the cost along. The cost involved is not comparable to standard insurance. Force-placed insurance is more expensive than a standard homeowner’s policy and can cost four to ten times more. And it provides dramatically less protection than what the homeowner previously had. Force-placed insurance covers only the loan’s remaining balance, not the actual property value. It does not cover personal property or liability claims. If a property is valued at $500,000 with a remaining mortgage balance of $15,000, the force-placed policy would likely provide only $15,000 in coverage. In other words, the homeowner pays far more for far less, a policy that protects the bank and leaves them exposed. The path from force-placed insurance to foreclosure is shorter than most people realize. A homeowner whose monthly mortgage payment suddenly increases by hundreds of dollars due to a lender-placed insurance premium, with no warning and no ability to opt out, may miss a payment. That late payment triggers additional fees and damage to credit. Many homeowners are surprised to learn that a lapsed insurance policy can trigger a costly lender-placed policy added directly to their mortgage balance,
Riverside County Real Estate: Lot Splits vs ADUs in 2026—Which Strategy Is Reshaping Housing Growth?
Riverside County has become one of the most closely watched real estate markets in Southern California, largely because it sits at the intersection of affordability pressure and policy-driven housing expansion. As coastal counties like Los Angeles and Orange continue to experience extreme price escalation, Riverside has absorbed a steady wave of migration from buyers seeking more attainable entry points into homeownership and investment properties. At the same time, California’s evolving housing laws are reshaping how property owners can maximize land use. Two of the most impactful tools driving this shift are SB9 lot splits and Accessory Dwelling Units (ADUs). Both strategies are designed to increase housing supply on existing residential land, but they function very differently in practice. SB9 focuses on subdividing land and creating additional primary units, while ADUs add secondary living spaces without changing the underlying parcel structure. In Riverside County, where single-family zoning still dominates but development pressure is increasing, the comparison between these two approaches has become a defining issue for homeowners, builders, and investors in 2026. Understanding how each option performs in terms of cost, approval speed, and long-term value is essential for anyone navigating this evolving market. Understanding the Two Housing Strategies SB9 Lot Splits: Creating New Parcels and Ownership Paths SB9 allows qualifying homeowners in single-family zones to split one parcel into two and build up to two units per lot, effectively creating up to four housing units in total under specific conditions. This law applies across California, including Riverside County, though local restrictions and eligibility rules still apply. To qualify, properties must meet strict criteria related to zoning, environmental risk, and land conditions. For example, parcels located in high fire zones, flood areas, or protected environmental regions may be excluded or require additional approvals. Even when eligible, SB9 developments are processed through ministerial review, meaning cities cannot require public hearings or discretionary approvals, which significantly reduces political delays. However, the process is still complex in practice. Developers must handle utility separation, new parcel mapping, and infrastructure adjustments, all of which add cost and time. In Riverside County, SB9 is often viewed as a long-term value strategy rather than a quick development solution. ADUs: Incremental Density on Existing Lots Accessory Dwelling Units (ADUs) operate under a different framework. Instead of dividing land, they add secondary housing units—either attached, detached, or converted structures—on an existing parcel. California state law requires cities and counties to allow ADUs with streamlined approvals and minimal barriers. In Riverside, homeowners can typically build at least one ADU on a residential lot, with setbacks as low as four feet and simplified permitting processes compared to traditional development. ADUs can reach up to 1,200 square feet depending on design and local compliance, and they are increasingly used for rental income, multigenerational housing, or long-term property value enhancement. Unlike SB9, ADUs do not require land subdivision, making them significantly easier and faster to implement. Cost and Feasibility Comparison in Riverside County SB9 Costs and Complexity SB9 projects tend to be capital-intensive. Costs include: Land surveying and subdivision mapping Utility separation for new parcels Infrastructure extensions (water, sewer, electrical) Construction of additional primary units In many cases, total development costs can exceed six figures before construction even begins. Additionally, financing can be more complex because lenders evaluate SB9 projects similarly to small-scale subdivisions rather than simple home improvements. The upside, however, is long-term value creation. A successful SB9 project can effectively transform a single property into two independently sellable assets, significantly increasing total property value. ADU Costs and Accessibility ADUs are generally more cost-effective and accessible. In Riverside County, basic detached ADUs often range from moderate to high five-figure or low six-figure construction budgets depending on size, materials, and utility connections. Converted garage units tend to be the most affordable entry point. Because ADUs do not require land division, permitting is faster and financing is simpler. Many homeowners use equity lines of credit or construction loans to fund projects. The return is typically generated through rental income rather than property division. Market Trends Driving Both Strategies Several key trends are influencing the growing use of both SB9 and ADUs in Riverside County: 1. Inland Migration Riverside continues to absorb demand from Los Angeles and Orange County, where median home prices often exceed $1 million. This migration increases rental demand and makes ADU construction financially attractive. 2. Affordability Pressure With interest rates remaining elevated through 2025–2026, buyers are relying more on multi-unit strategies to offset mortgage costs. ADUs are particularly popular because they generate immediate rental income. 3. State Housing Mandates California’s broader housing strategy continues to push for increased density through both subdivision (SB9) and incremental development (ADUs), ensuring both tools remain relevant in long-term planning. Key Differences in Practical Outcomes In Riverside County, the distinction between SB9 and ADUs is not just legal—it is strategic.SB9 is about ownership expansion It creates additional parcels and long-term equity growth but requires more capital and patience. ADUs are about income generation They provide faster returns through rental income and are easier to implement on most properties. In many cases, homeowners are now combining both strategies—using SB9 for long-term wealth building while adding ADUs for immediate cash flow. Riverside County sits at a critical point in California’s housing evolution. As demand continues to shift inland, property owners are increasingly looking for ways to maximize value from existing land. SB9 lot splits and ADUs represent two very different but complementary strategies that reflect this new reality. SB9 offers long-term structural transformation of property ownership, while ADUs provide immediate, flexible income opportunities. Neither approach is universally better; instead, their value depends on financial goals, property conditions, and development capacity. What is clear is that Riverside is no longer just an affordability alternative—it is becoming a laboratory for California’s new housing model, where land use, policy, and investment strategy are increasingly intertwined. Thank you for taking the time to read and reflect. I write to help people think clearly about money, business, real estate, and life — not
Homeownership Part 3: When You Own Your Home But Can’t Afford to Keep It
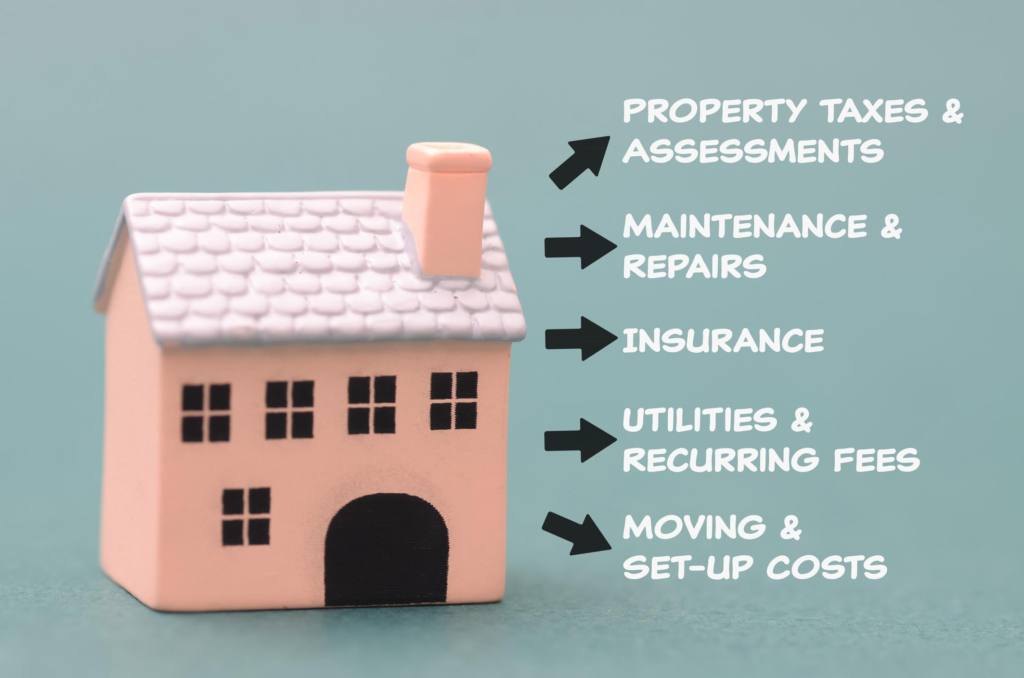
The story of homeownership in America has always been told as a story of arrival. You save, you sacrifice, you get your keys, and from that point forward you are building something, equity, stability, a foundation for your family’s future. The mortgage payment becomes the finish line. Everything after that is the reward. That framing leaves out a chapter that an increasing number of homeowners are living through right now. The chapter that comes after the closing. The one where the costs don’t stop, they just change form. Where the monthly mortgage payment, fixed and familiar, is joined by a growing roster of expenses that don’t stay fixed at all. Where people who did everything right, who bought responsibly and paid faithfully for years, find themselves financially squeezed not by a loan they couldn’t afford, but by costs they never saw coming. It is a quiet crisis happening inside what is supposed to be the ultimate financial achievement, and it is affecting tens of millions of American households. The numbers that define the problem The Harvard Joint Center for Housing Studies put the shape of this problem into clear relief in a 2025 research brief that deserves far more attention than it received. While mortgages remained the largest single housing expense for most homeowners, non-mortgage costs, home insurance, property taxes, utilities, and routine home maintenance, have increased more rapidly since the pandemic. This has raised costs and burden rates even for homeowners who have locked in historically low interest rates on their mortgages. That last detail is critical. These are not people who stretched to buy more than they could afford. These are people who bought conservatively, secured low rates, and are still struggling, because the costs surrounding the mortgage have outpaced what their incomes can absorb. The number of homeowners with cost burdens, defined as paying more than 30% of their income on housing costs, rose by 650,000 households in 2023 to a total of 20.3 million, representing 23.7% of all homeowner households. Nearly one in four homeowners in the United States is now spending more than the federally recognized threshold of affordability on the basic costs of keeping their home. And the trend is moving in the wrong direction. Median monthly owner costs for U.S. homeowners with a mortgage increased to $2,035 in 2024, up from $1,960 the year before, a 3.8% increase that outpaced the prior year’s growth rate. The hidden costs add up to a figure most prospective buyers never see in their pre-purchase calculations. According to Bankrate’s 2025 analysis, the average homeowner spends $8,808 per year on maintenance alone, nearly double the $4,494 spent on utilities and energy, double the $4,316 in annual property taxes, and four times the average $2,267 in home insurance premiums. Add those figures together and the total approaches $21,000 per year in non-mortgage costs, costs that don’t appear in the mortgage payment, don’t show up in affordability calculators, and rarely come up in conversations about whether someone can afford to buy. Nearly half of homeowners in Bankrate’s 2025 survey who expressed regret about buying cited maintenance and hidden costs as being more expensive than expected, making it the single most common source of homebuyer remorse. Who is bearing the heaviest weight The burden of rising ownership costs is not distributed evenly, and understanding who is most affected matters for how we think about solutions. Cost burdens are disproportionately faced by Black and Hispanic homeowners and are rising most rapidly for single-person and single-parent households who rely on a single income to cover housing costs. For households where one paycheck has to cover everything, the mortgage, the insurance spike, the property tax increase, the broken furnace, there is no financial buffer to absorb an unexpected cost increase. One bad year of insurance premiums or one major repair can tip a household from burdened to severely burdened, defined as spending more than 50% of income on housing. Between 2019 and 2023, 1.7 million homeowners aged 65 and over became cost-burdened, accounting for 47% of the total increase in burden nationwide. This brings the total number of burdened senior homeowners to 7.9 million, or 27.6% of all homeowners in that age group. This is a particularly acute dimension of the problem because older homeowners on fixed incomes have almost no mechanism to increase their revenue when costs rise. They cannot take on extra work. They cannot renegotiate a pension. They own their homes outright in many cases, meaning the mortgage finished decades ago, but the costs of insurance, taxes, utilities, and maintenance have grown to absorb what should have been the most financially comfortable chapter of their lives. The cost burden rate for the 11 million homeowner households earning below $30,000 per year reached 74.2% in 2023, the highest rate recorded in over 20 years, surpassing even the previous peak following the Great Recession. Three quarters of the lowest-income homeowners in America are spending more than 30% of what they earn just to stay in their homes. This is not a marginal problem or a regional curiosity. It is a widespread, worsening condition that the standard housing affordability narrative, focused almost entirely on purchase prices and mortgage rates, consistently fails to capture. The forces driving costs upward Several distinct pressures are converging to push non-mortgage ownership costs higher, and they are unlikely to reverse on their own. Insurance is perhaps the most visible. The average annual cost of home insurance rose 12% in 2025 and is projected to rise another 4% in 2026, driven in part by rising rebuilding costs and growing climate-related risks including hurricanes, floods, and wildfires. Homeowners in climate-exposed regions, coastal areas, wildfire zones, flood plains, are seeing premium increases that are not modest adjustments but structural repricing of risk. In some markets, insurers have withdrawn entirely, leaving homeowners with state-run last-resort coverage that is both more expensive and less comprehensive than private alternatives. Climate costs extend beyond insurance. A National Bureau of Economic Research study found that American